LV= life insurance review 2026
A look at LV=’s life insurance policies, included benefits, claims record and independent ratings.
- Trustpilot
- 4.5 / 5
- 86,748 reviews · whole LV= brand
- Defaqto
- 3–5 stars
- Life assurance categories
- Life claims paid
- 98%
- LV=, 2025
- Entry age
- 17–84
- 5–50 year terms
In a nutshell
LV= is a UK life and pensions mutual with a history dating back to 1843, and it reported paying 98% of life claims in 2025. It sells term life insurance, with or without critical illness cover, directly at lv.com, and a wider range of protection policies through financial advisers and LifeSearch.
- Sells level and decreasing term life insurance, and life insurance with critical illness cover, as single or joint policies.
- Critical illness cover is only sold with life insurance, not on its own.
- Terminal illness cover is included at no extra cost, and Life Protection premiums stay fixed unless you choose inflation-linked cover.
- Available to UK residents aged 17 to 84 (17 to 64 with critical illness cover) for terms of 5 to 50 years, with no minimum or maximum cover.
- Direct customers get free access to LV= Doctor Services, including a 24/7 remote GP, and a 24-hour Legal Advice Line.
- LV= reported paying 98% of life insurance claims and 90% of critical illness claims in 2025.
- Scores 4.5 out of 5 on Trustpilot across the whole LV= brand (including LV= General Insurance, part of the Allianz Group) and 3 to 5 Defaqto stars for life cover.
- Buying directly at lv.com may qualify you for an e-Gift card worth up to £400 after your 6th monthly premium.
- Over 50s and whole of life plans are closed to new customers, though existing policyholders can still claim.
Who are LV=?
LV= is a registered trademark of Liverpool Victoria Financial Services Limited, the UK mutual that provides LV= life insurance and pays its claims. Founded in 1843, LV= has no external shareholders and is run for the benefit of its members. It says over one million members and customers trust it with their futures, families and finances.
- Life insurer
- Liverpool Victoria Financial Services Limited
- FCA / PRA firm reference
- 110035
- Registered in England
- No. 12383237
- Company type
- Mutual, limited by guarantee
- Registered office
- County Gates, Bournemouth, Dorset, BH1 2NF
- Members and customers
- Over one million
The mutual began at 37 Blake Street, Liverpool, when customs officer William Fenton and a group of friends formed ‘The Liverpool Independent Legal Victoria Burial Society’. For many years it sold Industrial Branch Whole of Life Insurance, known as ‘penny policies’.
-
1843
The Liverpool Independent Legal Victoria Burial Society is formed in Liverpool
-
1930
Victoria House in Bloomsbury Square, London, becomes the head office
-
1996
LV= moves to Bournemouth
-
2001
Permanent Insurance acquired
-
2007
Starts trading as LV=
-
2016
Teachers Assurance acquired
-
2019
General insurance business sold to Allianz
-
2020
Converts from a friendly society to a company limited by guarantee
-
2021
Members reject a sale to Bain Capital
On 31 December 2019, LV= sold its general insurance business to Allianz Holding plc. LV= General Insurance, which covers cars, homes and pets, is now part of the Allianz Group and no longer part of Liverpool Victoria. It still uses the LV= name under a brand licence.
In December 2021, LV=’s members rejected a sale of the company to Bain Capital for a reported £530m. Former Bupa chief executive David Hynam became Chief Executive in September 2022, and Simon Moore is Chair.
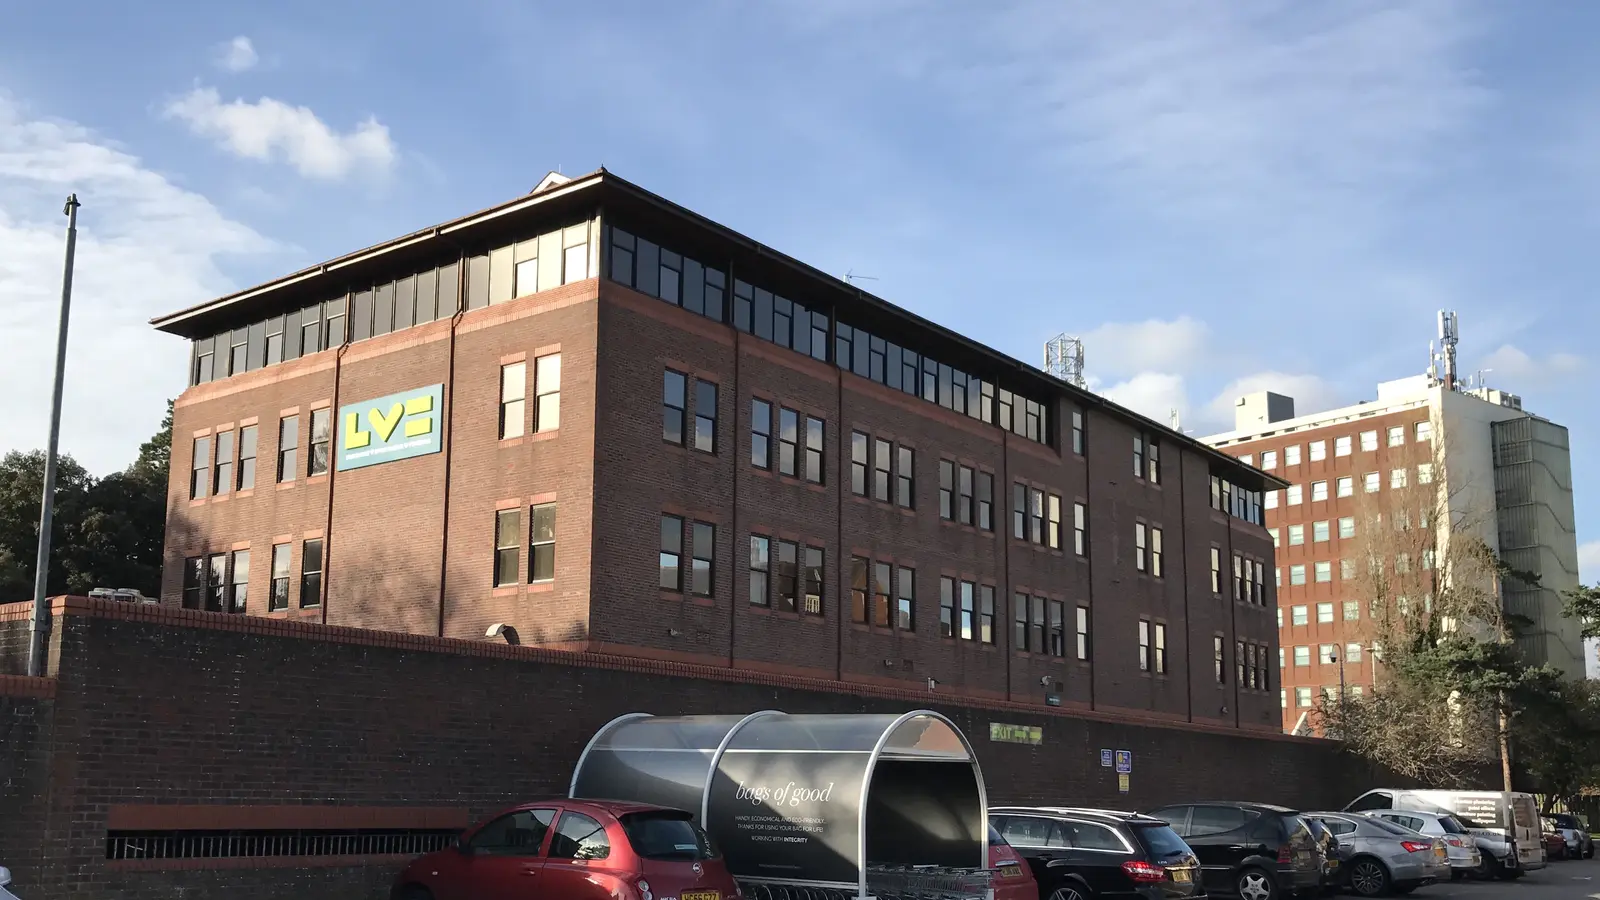
LV=’s head office is in Bournemouth, with further offices in Exeter and Hitchin. Taking out Life Protection makes you a member of the mutual, and LV= says it shared £100m in bonuses with eligible members in 2025.
Liverpool Victoria Financial Services Limited is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. The FCA register also warns of a clone firm using the name ‘Liverpool Victoria Financial Services’.
LV= says most of its customers buy through financial advisers. You can buy Life Insurance and Life & Critical Illness directly at lv.com without advice, or use LifeSearch or a financial adviser for its fuller range.
Compare quotes from a panel of UK insurers
- Quick 3 step process
- 60 second form
- Free quotes, no obligation
LV= life insurance ratings and reviews
LV= scores 4.5 out of 5 on Trustpilot across its whole brand and 3.50 out of 5 for life insurance on Smart Money People. The brand-wide scores on Trustpilot, Smart Money People and Reviews.io include LV= General Insurance (Allianz’s car, home and pet business), so they reflect more than life insurance alone.
| Review site | Rating | What it means |
|---|---|---|
| Trustpilot | 4.5 / 5 · Excellent | Based on 86,748 reviews across the whole LV= brand, including LV= General Insurance. 79% of reviewers gave 5 stars and 5% gave 1 star, with 5,641 reviews left in the last 12 months. LV= invites customers to leave reviews. View on Trustpilot (opens in a new tab) |
| Smart Money People | 4.08 / 5 · Good | Based on 619 product reviews across all LV products, including car, home and pet insurance. Life insurance on its own scores 3.50 from 51 reviews, and income protection scores 2.83 from 15 reviews. The profile is listed as an unverified business. View on Smart Money People (opens in a new tab) |
| Defaqto | 2–5 stars | Defaqto rates each product from 1 to 5 stars. LV=’s policies score between 2 and 5 stars, depending on the product and category. View on Defaqto (opens in a new tab) |
| Fairer Finance | 68.00% | A customer experience score for life insurance, reviewed in Spring 2026. It combines a 70.00% claims score, 63.72% for complaints performance and a 70.28% transparency rating. View on Fairer Finance (opens in a new tab) |
| Reviews.io | 3.6 / 5 | Based on 19 reviews across the LV= brand, including general insurance customers. 58% of reviewers recommend LV=. View on Reviews.io (opens in a new tab) |
Defaqto ratings for each LV= policy
LV=’s combined life and critical illness products earn 5 stars in every life assurance and critical illness category Defaqto rates them in. Its life-only policy, Life Protection, gets 3 stars for level term cover and 4 stars for decreasing cover.
LV=’s income protection products score 4 or 5 stars. The Flexible Protection Plan, which Life Protection is part of, gets 2 stars in Defaqto’s protection menu plan category.
| Policy | Range | Defaqto rating |
|---|---|---|
| Level term life insurance | Life Protection | 3 out of 5 stars |
| Level term life insurance | Life and Critical Illness Cover | 5 out of 5 stars |
| Level term life insurance | Life and Enhanced Critical Illness | 5 out of 5 stars |
| Level term life insurance | Life and Enhanced CI with Enhanced Children’s CI | 5 out of 5 stars |
| Decreasing term life insurance | Life Protection | 4 out of 5 stars |
| Decreasing term life insurance | Life and Critical Illness Cover | 5 out of 5 stars |
| Decreasing term life insurance | Life and Enhanced Critical Illness | 5 out of 5 stars |
| Decreasing term life insurance | Life and Enhanced CI with Enhanced Children’s CI | 5 out of 5 stars |
| Level term critical illness cover | Life and Critical Illness Cover | 5 out of 5 stars |
| Level term critical illness cover | Life and Enhanced Critical Illness | 5 out of 5 stars |
| Level term critical illness cover | Life and Enhanced CI with Enhanced Children’s CI | 5 out of 5 stars |
| Decreasing term critical illness cover | Life and Critical Illness Cover | 5 out of 5 stars |
| Decreasing term critical illness cover | Life and Enhanced Critical Illness | 5 out of 5 stars |
| Decreasing term critical illness cover | Life and Enhanced CI with Enhanced Children’s CI | 5 out of 5 stars |
| Income protection | Flexible Protection Plan Income Protection | 5 out of 5 stars |
| Income protection | Flexible Protection Plan Income Protection Budget | 5 out of 5 stars |
| Income protection | Personal Sick Pay | 4 out of 5 stars |
| Income protection | Personal Sick Pay – Budget | 4 out of 5 stars |
| Protection menu plan | Flexible Protection Plan | 2 out of 5 stars |
Ratings checked on 24 September 2026 and may have changed since. Defaqto ratings: defaqto.com (opens in a new tab)
Defaqto scores LV=’s critical illness policies higher than its life-only Life Protection plan. LV= says Life Protection has a 5-star rating from myTribe. On Smart Money People, LV= life insurance on its own scores 3.50 out of 5, lower than the brand-wide Trustpilot score.
Reviews tend to focus on moments such as claims and customer support, so it’s worth reading some recent life insurance reviews as well as the headline score.
What does LV= life insurance cover?
LV= life insurance pays out a lump sum if you die or are diagnosed with a terminal illness during the policy term. It only pays out once, so a terminal illness payout ends the policy and nothing further is paid on death.
You can insure yourself on a single policy, or take out a joint policy covering two people. A joint policy typically pays out on the first death, after which the cover ends.
LV= sets no minimum or maximum cover amount, and you can choose a policy term from 5 to 50 years. Your loved ones could use the payout to help with:
- Mortgage or rent payments
- Household bills and everyday living costs
- Childcare, school or university costs
- Outstanding loans and credit cards
- A cash gift or inheritance for the people you love
If the person insured dies, LV= normally pays the lump sum to their estate, where inheritance tax may apply. If you nominate beneficiaries on a Life Protection policy or place your policy in trust, LV= can pay out without waiting for probate.
When you buy directly at lv.com, LV= doesn’t give advice on whether the policy suits your needs. If you want independent advice on protection products, LV= has partnered with LifeSearch.
LV= life insurance policy options
LV= sells term life insurance, which runs for 5 to 50 years and pays out if you die or are diagnosed with a terminal illness during that time. Directly at lv.com, you can choose level or decreasing cover, with or without critical illness cover.
-
Level termThe payout and the premiums stay the same throughout the term.
-
Decreasing termThe payout reduces over the term, in line with a capital and interest repayment mortgage.
-
Life & critical illnessAlso pays out if you’re diagnosed with a covered critical illness.
Level term life insurance
Level term cover pays the same lump sum whenever a claim happens during the term. People often use it to protect family living costs or an interest-only mortgage where the loan balance doesn’t fall.
With LV= level cover, both your cover amount and your monthly premiums stay fixed for the whole term. UK residents can apply aged 17 to 84 for a term of 5 to 50 years, ending before their 90th birthday.
On Life Protection, you can also choose inflation-linked cover, which raises your cover each year with the Retail Prices Index (RPI) and your premium by RPI multiplied by 1.5. For inflation-linked cover, the maximum entry age is 79 and cover must end by age 85.
Decreasing term life insurance
With decreasing term cover, the payout reduces over time, roughly in line with a repayment mortgage. Because the cover amount falls over the term, premiums are usually lower than for level cover of the same starting size.
LV= designs its decreasing cover for capital and interest repayment mortgages and says it isn’t suitable for interest-only mortgages. Your cover reduces each month down to zero at the end of the term, while your premium stays fixed.
On a Life Protection claim, LV= normally pays the remaining mortgage balance from the date of death or terminal illness diagnosis, provided its mortgage conditions are met. If there’s no longer a mortgage, or those conditions aren’t met, it pays what would have been outstanding on a loan of the same amount and term at 6% interest, compounded annually.
Life insurance with critical illness cover
At LV=, you can only buy critical illness cover combined with life insurance. Life and Critical Illness pays out if you’re diagnosed with a covered critical illness or die during the term. LV= says it covers 41 conditions in total: 39 full payment conditions (including optional total permanent disability) and 2 additional payment conditions.
The two additional payment conditions are ductal or lobular carcinoma in situ of the breast (with specified treatment) and prostate cancer. They pay the lower of 25% of your cover or £30,000, leaving your main policy in place. Nine full payment conditions also pay an extra 50% (up to £200,000) if caused directly by an accident.
To claim for a critical illness, you must survive at least 14 days after diagnosis or surgery, and a doctor in a listed place must confirm it. The policy normally ends after one claim, unless it’s for an additional payment condition or children’s cover. LV= says its definitions meet or exceed the ABI Guide to Minimum Standards for Critical Illness Cover (2022).
UK residents aged 17 to 64 can apply for 5 to 50 years, ending before anyone insured turns 80, with no minimum or maximum cover. Total permanent disability, inflation-linked cover (entry ages 17 to 59) and waiver of premium are only available through a financial adviser.
Life and Enhanced Critical Illness
Available through financial advisers and LifeSearch, Life and Enhanced Critical Illness covers 87 conditions in total, including 49 full payment definitions. Total permanent disability and waiver of premium are optional extras. Additional payment conditions pay 50% of your cover up to £30,000 without ending the policy.
For 17 highlighted conditions, enhanced claim payments double your payout, with the extra payment capped at £200,000. The policy includes standard children’s cover at no extra cost and pays £1,000 on evidence of a covered cancer diagnosis, to help with costs such as travel or childcare.
Joint life insurance
A joint policy covers two people under one plan and pays out only once: it won’t pay out twice if both of you die or become terminally ill. Spouses and civil partners can apply directly to LV=, with the payout going to the surviving partner.
If you divorce, dissolve a civil partnership or legally separate, you can split a joint Life Protection policy into two single policies within six months, provided both partners agree.
At lv.com you can only insure yourself or take out a joint policy. Insuring someone else requires a financial adviser, and you must show you’d suffer financially if they died or became terminally ill.
Family income benefit
Family Income Benefit pays a tax-free monthly income until the end of the term if the person insured dies or is diagnosed with a terminal illness. Beneficiaries can swap the monthly payments for a reduced lump sum, or use the ‘Pay My Mortgage’ facility to have payments sent straight to their mortgage lender.
It’s available to people aged 17 to 84 for level cover (ending before 90) or 17 to 79 for inflation-linked cover (ending before 85). Terms run from 5 to 50 years, premiums are guaranteed for the whole term, and the minimum premium is £5 a month.
Income protection
LV= Income Protection replaces up to 60% of your monthly earnings if illness or injury stops you doing your usual job. You can apply aged 17 to 59 for a term of at least 5 years, ending before age 70. Waiting periods are 3, 6 or 12 months, or 1 or 2 months depending on your job.
The policy includes fracture cover, rehabilitation support, a £1,500 benefit guarantee and up to £10,000 of death benefit. LV= also has Budget Income Protection (paying for 12 or 24 months per claim) and Personal Sick Pay for riskier jobs. You can’t get an income protection quote directly from LV=: LifeSearch quotes it alongside other providers’ plans.
Buying LV= cover at lv.com vs through LifeSearch
LV= sells Life Insurance and Life & Critical Illness directly at lv.com, while its wider protection range and extra options are available through LifeSearch or a financial adviser:
| Feature | Direct at lv.com | Adviser or LifeSearch |
|---|---|---|
| Level or decreasing cover | Included | Included |
| Insuring someone else | Not available | Included |
| Inflation-linked cover | Not available | Included |
| Total permanent disability (with critical illness) | Not available | Optional |
| Waiver of premium (with critical illness) | Not available | Optional |
| Life and Enhanced Critical Illness | Not available | Included |
| Income protection quotes | Not available | Included |
| Advice on whether the policy suits you | Not available | Included |
| e-Gift card offer | Included | Not available |
Based on LV=’s product pages and policy summaries, checked 25 September 2026.
LV= life insurance at a glance
These are the main limits for LV=’s policies with level or decreasing cover. Inflation-linked cover has lower entry ages.
| Limit | Level term | Decreasing term | Life & critical illness |
|---|---|---|---|
| Age when you apply | 17–84 | 17–84 | 17–64 |
| Cover must end before | 90th birthday | 90th birthday | 80th birthday |
| Policy term | 5–50 years | 5–50 years | 5–50 years |
| Minimum or maximum cover | None | None | None |
| Single or joint | Both | Both | Both |
| Conditions covered | — | — | 41, incl. optional total permanent disability |
Limits from LV= product pages and policy summaries, checked 25 September 2026.
What affects the cost of LV= life insurance?
LV= says its life insurance starts from £5 a month, with your premium based on your personal details and the cover you pick. LV= lists these factors for its life and critical illness policies:
- Your age
- Your health, including whether you smoke
- Your lifestyle, such as alcohol and high-risk hobbies
- Your job (listed for critical illness cover)
- Your family’s medical history (listed for critical illness cover)
- How much cover you want
- How long you want cover for
Life Protection premiums are paid by monthly Direct Debit and stay fixed for the whole term unless you choose inflation-linked cover. The monthly premium includes a fixed fee for administration and support costs, and LV= tells advisers that a Flexible Protection Plan with more than one cover in it gets a small discount.
With any insurer, cover usually costs less the younger and healthier you are when you apply, and decreasing cover usually costs less than level cover. Adding critical illness cover raises the premium. Comparing quotes from several insurers shows what’s available for your circumstances.
LV= life insurance benefits & extras
LV= includes terminal illness cover at no extra cost on its life policies, along with free access to LV= Doctor Services and a 24-hour Legal Advice Line. Depending on the policy you hold, these features are included:
| Benefit | What it does | Available with |
|---|---|---|
| Terminal illness cover | On Life Protection, this pays out if you have an incurable illness and your specialists and LV=’s chief medical officer agree you’re not expected to live more than 12 months. The policy ends once the claim is paid. | Available with: Life Protection and Family Income Benefit, and a listed condition on Life and Critical Illness |
| Guaranteed increase options | Lets you raise your cover without further health questions within three months of events such as marriage, divorce, having a child, a higher rent or mortgage, or a basic pay rise of at least 10%. Each increase can add up to £150,000 (capped at 50% of your cover, and £200,000 across the policy) while the insured person is 54 or under. | Available with: Life Protection |
| Beneficiary nomination | Name up to 10 beneficiaries when you apply and choose each person’s share, so LV= can pay them without waiting for probate. You can update your nominated beneficiaries later, though placing the policy in trust overrides them. | Available with: Life Protection |
| Separation option | Split a joint policy into two single policies within six months of a divorce, civil partnership dissolution or legal separation, with both partners’ agreement. | Available with: Joint Life Protection policies |
| Accident payments | Pays an extra 50% of your cover, capped at £200,000, if one of nine full payment critical illness conditions is caused directly by an accident. | Available with: Life and Critical Illness |
| LV= Doctor Services | Six medical services from Square Health, by app or phone. You and your spouse or partner (at the same address) get a 24/7 remote GP with a UK doctor and 25% off health MOTs, and you share up to 5 remote physiotherapy and 5 psychological sessions a year. Children up to 16 can use the remote GP, prescriptions and second opinions. It’s non-contractual, so LV= can change or remove it at any time. | Available with: Direct Life Protection and Life with Critical Illness policies, plus eligible protection policies bought through an adviser |
| Legal Advice Line | 24-hour access to free legal advice from Lyons Davidson Solicitors on 0800 876 6166 (option 1). | Available with: LV= members with a specific protection product |
You can also add these for an extra cost, depending on the policy and how you buy it:
| Optional extra | What it does |
|---|---|
| Children’s critical illness cover | Covers your children, including stepchildren and adopted children, from birth to their 23rd birthday, for 95 conditions. It pays 50% of your cover up to £35,000, or the lower of 25% of your cover or £15,000 for a children’s additional payment condition. There’s no 14-day survival period, and it includes £5,000 towards a covered child’s funeral plus £5,000 per pregnancy for 6 pregnancy complications. It’s an optional add-on on Life and Critical Illness and included as standard on Life and Enhanced Critical Illness. |
| Waiver of premium | Covers your regular policy payments if illness or injury stops you working beyond your waiting period. Available to UK residents aged 17 to 59, it pays no money itself and can’t be taken on its own. On Life and Critical Illness it can only be added through a financial adviser. |
| Total permanent disability | Covers you if illness or injury leaves you permanently unable to do the main aspects of your normal occupation. On Life and Critical Illness, it must be added at the start through a financial adviser. |
| Inflation-linked cover | Raises your cover each year with RPI inflation and your premium by inflation multiplied by 1.5. On Life and Critical Illness, it’s only available through a financial adviser. |
Writing an LV= policy in trust
You can put an LV= protection policy in trust when it starts or later, and LV=’s Online Trusts tool helps you choose a trust and set it up online. LV= offers fixed, flexible and split trusts, but not discretionary trusts.
When a policy is in trust, the trustees only need to send LV= the original death certificate and the original trust deed to claim, without waiting for probate. LV= says payouts from a trust aren’t normally counted in your estate for inheritance tax.
- A split trust lets you keep critical illness payouts while the life insurance payout goes into trust.
- LV=’s trust deeds automatically make you, the settlor, a trustee as well.
- For joint life policies that pay out on the first death, LV= has added a survivorship clause to its trust deeds. It’s opt-in and can only be chosen when the trust is set up.
- Putting a policy in trust is normally irrevocable, and a trust overrides any beneficiaries you nominated.
- Trusts holding LV= protection plans with no surrender value don’t need to be registered unless a claim is paid, and even then only in certain cases.
Read how trusts work, and what other insurers offer, in our guide to life insurance in trust.
LV= free gift offers
Note: Free gifts are offered by select brokers only, our life insurance brokers do not offer free gifts.
If you buy LV= Life Insurance or Life & Critical Illness directly at lv.com (from 17 August 2026) and are accepted, you may qualify for an e-Gift card worth up to £400. The card is sent after your 6th monthly premium and its value depends on your first monthly payment:
- £5–£9.99 a month
- £15 e-Gift card
- £10–£19.99 a month
- £30 e-Gift card
- £20–£29.99 a month
- £60 e-Gift card
- £30–£49.99 a month
- £100 e-Gift card
- £50–£59.99 a month
- £150 e-Gift card
- £60–£69.99 a month
- £200 e-Gift card
- £70–£79.99 a month
- £250 e-Gift card
- £80–£99.99 a month
- £300 e-Gift card
- £100 a month or more
- £400 e-Gift card
- Your 6th monthly premium must be paid in full on its due date. If it’s missed or only part-paid, you won’t get a card.
- LV= aims to email the card within 28 days of receiving your 6th premium. Edenred sends it, you pick a card from a selection on an online portal, and you must redeem it within 90 days of the reward email.
- You get one e-Gift card per policy (up to two per household in 12 months), sent to the first named policyholder on a joint plan.
- Only direct applications at lv.com qualify. Applying through LifeSearch, a financial adviser, an affiliate or a comparison website doesn’t count, and nor does being a cashback customer or having cancelled an LV= Life Insurance or Life & Critical Illness plan before.
- There’s no cash alternative, and the cards are non-refundable and non-transferable.
Offer terms checked on 25 September 2026. LV= can change the terms or withdraw the offer at any time.
See other insurers’ offers and their conditions in our guides to life insurance with a free gift and over 50 life insurance with a free gift.
Does LV= pay out?
Yes. In 2025, LV= reported paying 98% of life insurance claims and 90% of critical illness claims. It paid nearly £152 million across all its personal protection policies.
- Life claims paid
- 98%
- Critical illness claims paid
- 90%
- Paid in life claims
- £80m+
- Paid in all personal protection claims
- £151.7m
LV= claims paid by year
| Year | Life claims paid | Critical illness claims paid | Total paid (life) |
|---|---|---|---|
| 2025 | 98% | 90% | Over £80m |
| 2024 | 97% | 90% | Over £80m |
Source: LV= published claims figures for 2024 and 2025.
LV=’s 98% life figure includes Life Insurance, Family Income Benefit, terminal illness and whole of life plans (including some guaranteed over 50s policies), not just term cover.
Across all individual protection policies in 2025, LV= paid 95% of claims and supported more than 8,000 people and their families. Its annual personal protection payouts rose every year from £119m in 2021 to £151.7m in 2025, and in 2023 it paid over £87m in life claims across 5,500 families.
In 2025, the main causes of LV= life claims were cancer (40%), heart-related conditions (18%), respiratory conditions (11%), and dementia and stroke (4% each). The average life claimant was 66 (excluding 50+ plans) and the largest life payout was £1.1 million. For critical illness, cancer accounted for 60% of 2025 claims, ahead of heart attack (12%) and stroke (6%).
LV= is a 2025 signatory to the Protection Distributors Group (PDG) Claims Charter. It declined 5% of claims in 2025, mainly for misrepresentation or non-disclosure of smoking, alcohol use or medical history. LV= warns that inaccurate answers can lead to a declined claim or a cancelled policy.
How to make an LV= life insurance claim
You can report a death claim on a Life Protection policy on LV=’s website, by phone, by email or in writing. LV= asks for the policy number, the date of birth, date of death and address of the person who died, plus your contact details. Before paying out, LV= requires the original death certificate rather than a photocopy.
For a critical illness claim, LV= discusses your claim and sends a claims pack within 24 hours by post or email. Once LV= reaches its final decision, it aims to pay within 3 days. It normally pays Life Protection claims by bank transfer.
If the policy is held in trust, the trustees send the original death certificate and the original trust deed, and LV= pays out without waiting for probate. Existing over 50s policyholders have a separate claims phone line.
- Life claims phone
- 0800 756 5869
- Opening hours
- Mon–Fri, 9am–5pm
- Policies starting A, B, C, F, L, RN, T, U, V or X
- 0800 681 6294
- Calling from abroad
- +44 1392 366 685
- Claims email
- healthclaims@lv.com
- Claims address
- LV= Protection, PO Box 341, Abbey View, Wymondham, NR18 8HR
- Over 50s claims
- 0800 032 8390
Key policy terms
These are the main rules on cancelling, missed payments, exclusions and tax for LV=’s life and critical illness plans. Check the policy conditions for the exact product you’re offered.
| Term | LV= policies |
|---|---|
| Cooling-off period | 30 days from the start date, with a refund of premiums paid |
| Cancelling later | Cover ends and you get nothing back |
| Suicide exclusion | No death claim in the first 12 months; on Life Protection, LV= cancels the policy and refunds the premiums paid |
| Terminal illness | On Life Protection, an incurable illness where LV=’s chief medical officer and your specialists agree you’re not expected to live more than 12 months |
| Missed premiums | 60 days to make up missed payments; on Life Protection, cover continues during that time, and a lapsed policy can be restarted within six months after answering health questions |
| Premiums | Fixed once Life Protection starts, unless you chose inflation-linked cover; monthly Direct Debit only |
| Changing cover | On Life Protection, the type of cover can’t be changed once the policy starts, but the amount can be increased with a guaranteed increase option |
| Write in trust | Yes: fixed, flexible or split trusts, with an Online Trusts tool |
| Medical exam | Depends on your circumstances and medical history; LV= may ask your GP for a report, interview you by phone or ask for a health check |
| Cash-in value | None at any time |
| Residency | You must live permanently in the UK (not including the Channel Islands or the Isle of Man) |
| Where you’re covered | Death is covered worldwide; a terminal illness diagnosis must be confirmed by a doctor in a listed place, such as the UK, Ireland, the USA, Canada or Australia |
| Tax | Income tax and capital gains tax don’t currently apply to claims, but inheritance tax might |
| Wrong information | Deliberately withholding information or lying means the policy is cancelled with no refund; a genuine mistake can mean reduced cover, policy changes, a declined claim or cancellation |
| If LV= couldn’t pay | The Financial Services Compensation Scheme covers 100% of a Life Protection claim |
Is LV= life insurance good?
LV= is a long-established UK mutual that reported paying 98% of life claims in 2025. Its term life insurance includes terminal illness cover, fixed premiums, guaranteed increase options and beneficiary nomination, plus free access to LV= Doctor Services and a Legal Advice Line.
Defaqto gives LV=’s combined life and critical illness policies 5 stars, but scores the life-only Life Protection 3 stars for level cover. On Smart Money People, LV= life insurance scores 3.50 out of 5, which is lower than the brand-wide 4.5 on Trustpilot.
The direct range at lv.com is narrower than what LV= sells through LifeSearch or an adviser. Online, you can only insure your own life or a joint life, and enhanced critical illness cover, total permanent disability and inflation-linked critical illness cover need LifeSearch or an adviser. LV= also no longer sells new over 50s or whole of life plans. The right insurer for you depends on the cover you need and the price you’re offered, so it’s worth comparing a few.
Pros
- Long-established mutual with no external shareholders
- Reported paying 98% of life claims in 2025
- Terminal illness cover included at no extra cost
- No minimum or maximum amount of cover, with terms of 5 to 50 years
- Beneficiaries you nominate are paid without waiting for probate
- Free access to LV= Doctor Services and a Legal Advice Line
- Critical illness products rated 5 stars by Defaqto
Cons
- Life Protection rated 3 stars by Defaqto for level term cover
- Direct cover only on your own life or a joint life
- Total permanent disability and inflation-linked critical illness cover only through an adviser
- Doctor Services is non-contractual and can be changed or removed
- No over 50s or whole of life plans for new customers
- Life insurance scores 3.50 out of 5 on Smart Money People
- Policies have no cash-in value
LV= life insurance policy documents
Before you take out a policy, it’s worth reading the policy summary and policy conditions for the exact product you’re offered. These official LV= documents are a good place to start:
-
Life Protection policy summary (opens in a new tab)
An overview of LV= Life Protection, including who can be insured, the cover options, what isn’t covered and how to claim (45220-2025 02/25).
-
Life Protection policy conditions (opens in a new tab)
The full terms of the Life Protection contract, including definitions, options and exclusions (MIMILP17).
-
Life and Critical Illness policy summary (opens in a new tab)
An overview of Life and Critical Illness, including the conditions covered and the options available (45224-2025 02/25).
-
Life and Critical Illness policy conditions (opens in a new tab)
The full terms of Life and Critical Illness, including the critical illness definitions (FPPCLCI2G).
-
Our services explained (opens in a new tab)
Who provides LV=’s direct Life Insurance and Life with Critical Illness, and how LV= sells them without advice (45492-2025 02/25).
-
Our guide to trusts (opens in a new tab)
How LV=’s fixed, flexible and split trusts work, including the survivorship clause (45684-2025).
-
Waiver of Premium policy summary (opens in a new tab)
An overview of LV=’s Waiver of Premium policy, including who can take it and how waiting periods work (49034-2023 04/26).
-
Income Protection policy summary (guaranteed premiums) (opens in a new tab)
An overview of LV= Income Protection with guaranteed premiums (49025-2022 04/26).
-
Life and Enhanced Critical Illness product profile (opens in a new tab)
LV=’s adviser product profile for Life and Enhanced Critical Illness Cover (46174-2025 04/26).
-
Family Income Benefit product profile (opens in a new tab)
LV=’s adviser product profile for Family Income Benefit (46178-2025 04/26).
Documents are published by LV= and open on its websites. LV= may update them — the version you receive with your policy is the one that applies.
LV= life insurance FAQs
You can apply for LV= life insurance aged 17 to 84, and the policy must end before your 90th birthday. With critical illness cover, you can apply aged 17 to 64, and cover must end before anyone insured turns 80.
Yes. LV= reported paying 98% of life claims in 2025, more than £80 million to over 5,500 families. It also paid 90% of critical illness claims. The 98% life figure includes Family Income Benefit, terminal illness and whole of life policies alongside term life insurance.
LV= life insurance is provided by Liverpool Victoria Financial Services Limited, which is also responsible for paying claims. It’s a mutual owned by its members, and taking out Life Protection makes you a member.
Once LV= has made its final decision, it aims to pay a life or critical illness claim within 3 days. When you report a critical illness claim, LV= sends out a claims pack within 24 hours.
When you apply for cover you will be asked questions about your health and lifestyle, and based on this and the amount of cover requested, the insurer will decide if a medical is required or not.
LV= says it may ask your GP for a medical report, speak to you about your health and lifestyle by phone, or ask you to have a health check. LV= says its online application could cover you in less than 25 minutes, but some applicants need a fuller conversation or a GP report.
Yes. LV= offers fixed, flexible and split trusts (though not discretionary trusts), and its Online Trusts tool lets you set one up online. When a policy is in trust, LV= pays the trustees without waiting for probate.
No. LV= no longer sells over 50s life insurance or whole of life plans to new customers. If you already hold an LV= over 50s policy, you can still make a claim by calling 0800 032 8390 (Monday to Friday, 9am–5pm).
Yes. Life Protection has guaranteed increase options you can use without further health questions within three months of events such as marriage, divorce, having a child, a basic pay rise of at least 10% or a higher rent or mortgage. Each increase can add up to £150,000 and no more than 50% of your cover, up to £200,000 in total, while the person insured is 54 or under.
Yes, at any time. If you cancel within 30 days of the start date, LV= refunds the premiums you’ve paid. After that, your cover ends and you get nothing back, as the policy has no cash-in value.
LV= doesn’t pay a death claim if the person insured intentionally takes their own life within 12 months of the policy start date. On Life Protection, LV= cancels the policy and refunds the premiums paid so far.
If you're struggling or thinking about suicide, our guide to suicide and life insurance lists where to get support straight away.
Sources
The facts on this page come from these sources.
- Geograph Britain and Ireland — Geograph - Westbourne: Victoria House (photo 5294976, description of LV= headquarters buildings) (opens in a new tab), geograph.org.uk, accessed 25 September 2026.
- LV= — Life Protection policy conditions (MIMILP17) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - About us (who we are) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Information for members (mutual membership) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= press release (15 July 2026) - nearly £152 million paid in protection claims in 2025 (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — Flexible Protection Plan Life Protection product profile (46177-2025 05/25) (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= — Flexible Protection Plan Life and Critical Illness Cover product profile (46176 2025 05/25) (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= — LV= Life Insurance product page (with FAQs and e-Gift card offer terms) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Life and critical illness cover product page (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Income Protection Insurance page (sold through LifeSearch) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — Life and Critical Illness policy summary (45224-2025 02/25) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — Flexible Protection Plan Family Income Benefit product profile (46178-2025 04/26) (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= — Life and Critical Illness policy conditions (FPPCLCI2G) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — Life Protection policy summary (45220-2025 02/25) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Doctor Services page (eligibility and services) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Legal Advice Line page (eligible protection products) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria Financial Services Limited) — LV= Adviser - Claims (2025 claims figures for advisers) (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- Trustpilot — Trustpilot - LV= (www.lv.com) company reviews, all LV= brand products incl. LV= General Insurance (Allianz) (opens in a new tab), uk.trustpilot.com, accessed 25 September 2026.
- Defaqto — Defaqto Star Ratings (Life & Protection) for LV= (opens in a new tab), defaqto.com, accessed 24 September 2026.
- LV= (Liverpool Victoria) — LV= - Make an Over 50's Life Insurance claim (existing policies) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Adviser: Life Protection product page (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Our history (founding, head offices, acquisitions) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - LV= companies (legal entities in the Liverpool Victoria group) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Corporate governance (company limited by guarantee, board, acquisitions) (opens in a new tab), lv.com, accessed 25 September 2026.
- Companies House — Companies House - LIVERPOOL VICTORIA FINANCIAL SERVICES LIMITED (12383237) (opens in a new tab), find-and-update.company-information.service.gov.uk, accessed 25 September 2026.
- Wikipedia — Wikipedia - Liverpool Victoria (history and background only) (opens in a new tab), en.wikipedia.org, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Contact us (life, investments and retirement; bereavement; claims lines) (opens in a new tab), lv.com, accessed 25 September 2026.
- Financial Conduct Authority — FCA Financial Services Register - Liverpool Victoria Financial Services Limited (FRN 110035) (opens in a new tab), register.fca.org.uk, accessed 25 September 2026.
- LV= — Our services explained (Life Insurance and Life with Critical Illness, 45492-2025 02/25) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Product legal information (which LV= company provides each product, complaints, FSCS) (opens in a new tab), lv.com, accessed 25 September 2026.
- Smart Money People — Smart Money People - LV (Liverpool Victoria) Life Insurance product reviews (opens in a new tab), smartmoneypeople.com, accessed 25 September 2026.
- REVIEWS.io — Reviews.io - LV= (www.lv.com) company reviews, all products (opens in a new tab), reviews.io, accessed 25 September 2026.
- Smart Money People — Smart Money People - LV (Liverpool Victoria) company reviews, all products (opens in a new tab), smartmoneypeople.com, accessed 25 September 2026.
- Smart Money People — Smart Money People - LV (Liverpool Victoria) Income Protection product reviews (opens in a new tab), smartmoneypeople.com, accessed 25 September 2026.
- Fairer Finance — Fairer Finance - LV= brand page (customer experience ratings by category, Spring 2026) (opens in a new tab), fairerfinance.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Our business (ratings and awards) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — FAQ: Who can I take out a Life Insurance policy on? (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — Our guide to trusts (45684-2025) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Adviser: Life and Critical Illness product page (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= — Flexible Protection Plan Combined Life and Enhanced Critical Illness Cover product profile (46174-2025 04/26) (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= — LV= Adviser: Family Income Benefit product page (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= — LV= Income Protection cover page (features, eligibility, documents) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — Income Protection policy summary, guaranteed premiums (49025-2022 04/26) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Adviser: Flexible Protection Plan (menu plan) page (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= — LV= Children's Critical Illness cover page (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — Waiver of Premium policy summary (49034-2023 04/26) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — LV= Life Insurance Trusts page (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= press release (30 April 2025) - almost £137 million paid in protection claims in 2024 (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= press release (24 April 2024) - protection claim payouts hit £135 million in 2023 (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria Financial Services Limited) — LV= Claims Report 2025 (adviser claims report, claims record 2021-2025) (opens in a new tab), lvadviser.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Life Insurance FAQ: Will you pay a Life Insurance claim? (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - How to make a Life Insurance with Critical Illness claim (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= (Liverpool Victoria) — LV= - Make a life insurance claim (claims phone numbers and hours) (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — FAQ: Can I change my mind about my Life Insurance cover? (opens in a new tab), lv.com, accessed 25 September 2026.
- LV= — FAQ: How long does it take to get Life Insurance? (opens in a new tab), lv.com, accessed 25 September 2026.
Related pages
-
Best life insurance
What to compare when you choose a policy.
-
Term life insurance
Cover for a set number of years, with level or decreasing cover.
-
Decreasing term life insurance
The payout falls over the term, often in line with a mortgage.
-
Joint life insurance
One policy for two people, compared with two single policies.
-
Family life insurance
Cover that helps your family with everyday costs.
-
Critical illness cover
A lump sum on diagnosis of a serious illness your policy covers.