NFU Mutual life insurance review 2026
A look at NFU Mutual’s life insurance policies, provided by Aviva, with their included benefits, claims record and independent ratings.
- Trustpilot
- 4.0 / 5
- 6,788 reviews · whole company
- Defaqto
- 5 out of 5 stars
- Level term (Aviva Life Insurance+)
- Life claims accepted
- 98.7%
- Aviva, 2025
- Entry age
- 18–89
- Term Assurance, 1–50 year terms
In a nutshell
A mutual insurer owned by its members that sells life cover through its own financial advisers and by phone, but no longer insures new policies itself: its current life cover and protection policies are provided by Aviva.
- Its Term Assurance is Aviva Life Insurance+: level, decreasing or family income cover for one person or two, with terms of 1 to 50 years, for ages 18 to 89 (from 78, the minimum cover is £50,000).
- NFU Mutual also sells Aviva’s Critical Illness+, Income Protection+ and Whole of Life Insurance+, plus business protection. Its current range has no over 50s plan.
- Terminal illness cover and free house purchase cover come with Life Insurance+, and NFU Mutual charges no advice fee on Aviva products because Aviva pays it commission.
- Defaqto rates Aviva’s Life Insurance+, Critical Illness+ and Income Protection+ 5 stars and Whole of Life Insurance+ 4 stars. Trustpilot scores NFU Mutual 4.0 out of 5 across all its products.
- Aviva, which provides the policies, reported accepting 98.7% of individual life claims and paying 90.7% of critical illness claims in 2025, across all its protection policies.
- Older policies are looked after by NFU Mutual (bought before April 2016) or by Aviva (bought from 1 August 2016), each with its own contact details.
Who are NFU Mutual?
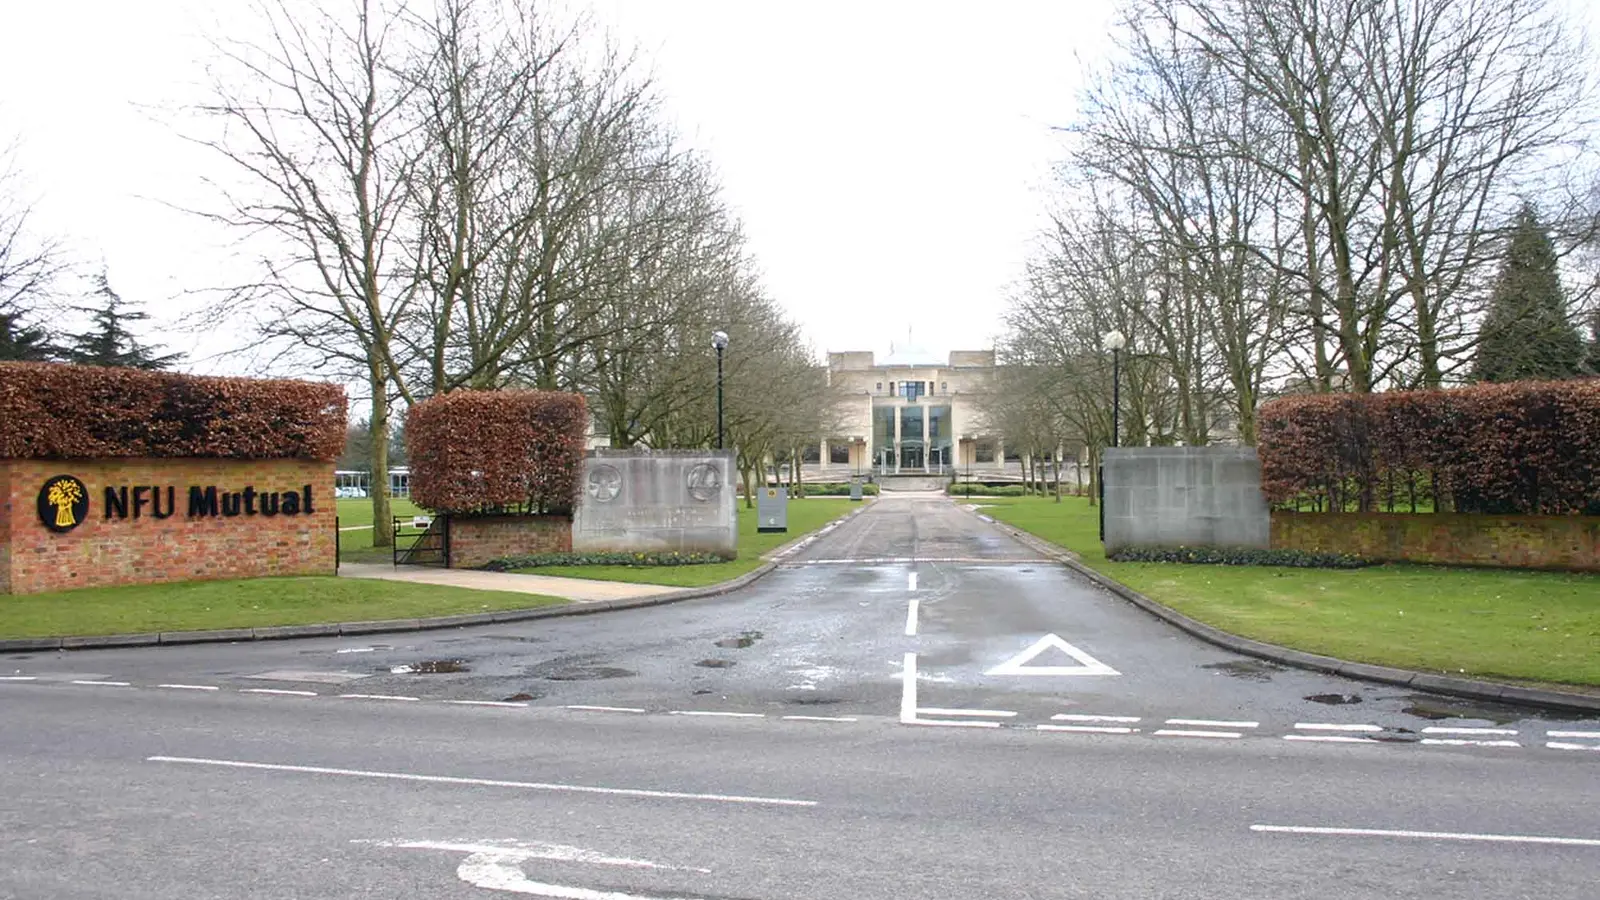
NFU Mutual is The National Farmers Union Mutual Insurance Society Limited, a mutual without shareholders that is owned by and run for its members. Its customers are members and can vote on resolutions at its AGM. It was founded in 1910, as the Midland Farmers Mutual Insurance Society Limited, and its registered office is on Tiddington Road in Stratford-upon-Avon.
- Life cover provided by
- Aviva Life & Pensions UK Limited
- Advice and sales
- NFU Mutual Select Investments Limited
- Society
- The National Farmers Union Mutual Insurance Society Limited
- FCA / PRA firm reference
- 117664
- Registered in England
- No. 00111982
- Registered office
- Tiddington Road, Stratford-upon-Avon, Warwickshire, CV37 7BJ
- Incorporated
- 30 September 1910
- Ownership
- Mutual, owned by its members
Alongside life cover it sells general insurance such as home, car and business insurance, as well as investments and pensions, and says it provides a local, personal service through a network of 280 agency offices and UK-only call centres. Its 2025 annual report refers to a team of more than 70 Financial Advisers, and NFU Mutual says it has been providing financial services for over 95 years and financial advice for over 90 years.
-
1910
Incorporated as the Midland Farmers Mutual Insurance Society Limited
-
1919
Takes the name The National Farmers Union Mutual Insurance Society Limited
-
2001
Shown on the FCA Register as authorised from 1 December 2001
-
2012
NFU Mutual Select Investments Limited, which now gives its financial advice, is incorporated
-
2016
NFU Mutual says life cover and protection policies bought from 1 August are administered by Aviva Protection UK Limited, then called AIG Life Limited
-
2025
AIG Life Limited is renamed Aviva Protection UK Limited in February; policies bought after 9 November are administered by Aviva Life & Pensions UK Limited
-
2025
Aviva Protection UK’s business transfers to Aviva Life & Pensions UK Limited on 31 December
For life cover, NFU Mutual now partners with Aviva. Its Term Assurance, Critical Illness Cover, Income Protection and Whole of Life Cover pages each name an Aviva policy, and the policy conditions it links to are the contract with Aviva Life & Pensions UK Limited. NFU Mutual’s 2025 annual report says the group no longer sells new protection business.
Advice is given by NFU Mutual Select Investments Limited, a wholly owned subsidiary that acts as an insurance intermediary for Aviva Life and Pensions UK Ltd. NFU Mutual offers restricted advice, on products from a limited number of companies, and it’s paid commission by Aviva rather than charging an advice fee on Aviva products.
NFU Mutual says policies bought between 1 August 2016 and 9 November 2025 are administered by Aviva Protection UK Limited, which was called AIG Life Limited until February 2025. Its board approved moving its long-term insurance business to its parent, Aviva Life & Pensions UK Limited, under a Part VII transfer; the court and regulatory permissions were obtained in 2025, and the transfer took effect on 31 December 2025. Policies bought before April 2016 are administered by NFU Mutual, which still supports customers who hold them.
NFU Mutual is authorised by the Prudential Regulation Authority and regulated by the FCA and the PRA, and the FCA Register shows it as authorised since 1 December 2001. It’s a member of the Association of British Insurers and says it’s covered by the Financial Services Compensation Scheme. It only provides its products in the United Kingdom.
Whether it’s the right choice for you depends on the cover you need and the price you’re offered, so it’s worth comparing plans before you decide.
Compare quotes from a panel of UK insurers
- Quick 3 step process
- 60 second form
- Free quotes, no obligation
NFU Mutual life insurance ratings and reviews
Here’s how NFU Mutual is rated by customers and by independent experts. The Trustpilot and Smart Money People scores cover NFU Mutual as a whole, so they reflect its service across all its products, while Fairer Finance rates NFU Mutual’s life insurance. Defaqto rates the Aviva policies NFU Mutual sells.
| Review site | Rating | What it means |
|---|---|---|
| Trustpilot | 4.0 / 5 · Great | Based on 6,788 reviews of NFU Mutual as a whole, 400 of them in the last 12 months. 79% are 5-star and 13% are 1-star, and NFU Mutual has replied to 79% of negative reviews. Trustpilot’s AI summary of 441 recent reviews says reviewers had a great experience, but Trustpilot also notes that NFU Mutual hasn’t invited customers to review recently, so the reviews may not be representative. View on Trustpilot (opens in a new tab) |
| Smart Money People | 4.58 / 5 · Excellent | Based on 141 product reviews across NFU Mutual’s products. View on Smart Money People (opens in a new tab) |
| Fairer Finance | 76% · No ribbon | NFU Mutual’s Autumn 2026 life insurance customer experience score, with 88% for claims, 72% for complaints and 67% for transparency. View on Fairer Finance (opens in a new tab) |
| Defaqto | 4–5 stars | Defaqto rates each product from 1 to 5 stars. It has no rating under NFU Mutual’s name: it rates the Aviva policies NFU Mutual sells under Aviva Life & Pensions UK Limited, from 4 stars for Whole of Life Insurance+ to 5 stars for Life Insurance+, Critical Illness+ and Income Protection+. See the ratings for each policy below. View on Defaqto (opens in a new tab) |
Defaqto ratings for the Aviva policies NFU Mutual sells
NFU Mutual’s Term Assurance, Critical Illness Cover, Income Protection and Whole of Life Cover are Aviva’s Life Insurance+, Critical Illness+, Income Protection+ and Whole of Life Insurance+. Defaqto lists them under Aviva Life & Pensions UK Limited, with the product names shown below.
| Policy | Range | Defaqto rating |
|---|---|---|
| Level term life insurance | Life Insurance+ and Life Insurance+ Upgraded | 5 out of 5 stars |
| Decreasing term life insurance | Life Insurance+ and Life Insurance+ Upgraded | 5 out of 5 stars |
| Level term with critical illness | Life Insurance+ and Life Insurance+ Upgraded | 5 out of 5 stars |
| Decreasing term with critical illness | Life Insurance+ and Life Insurance+ Upgraded | 5 out of 5 stars |
| Standalone critical illness | Critical Illness+ and Critical Illness+ Upgraded | 5 out of 5 stars |
| Income protection | Income Protection+ | 5 out of 5 stars |
| Whole of life insurance | Whole of Life Insurance+ | 4 out of 5 stars |
Ratings checked on 24 September 2026 and may have changed since. Defaqto ratings: defaqto.com (opens in a new tab)
Put together, the Aviva policies NFU Mutual sells have 5 stars from Defaqto, apart from Whole of Life Insurance+ with 4 stars. Customer scores for NFU Mutual as a whole are 4.0 out of 5 on Trustpilot and 4.58 out of 5 on Smart Money People, and Fairer Finance gives its life insurance 76%.
NFU Mutual’s own awards page shows its ratings for home, car and business insurance rather than for life cover.
Headline scores only tell part of the story, so it’s worth reading a selection of recent reviews as well.
What does NFU Mutual life insurance cover?
NFU Mutual’s Term Assurance is Aviva Life Insurance+, a term life insurance policy. It pays a lump sum or a monthly amount if the person covered dies during the policy term, or is diagnosed with a terminal illness and isn’t expected to live more than 12 months. Once Aviva accepts a claim and pays out, the policy ends.
You choose life cover, or life and critical illness cover, and whether it covers one person or two. On a joint policy the two people can have different cover, and the policy pays out when the first person claims, unless you choose life cover that only pays once both people have claimed.
NFU Mutual says its products can help repay a debt, like a mortgage, and that Life Insurance+ is designed to help reduce the financial burden on your family. More generally, the payout could help your family with:
- Mortgage or rent payments
- Household bills and everyday living costs
- Childcare, school or university costs
- Outstanding loans and credit cards
- A cash gift or inheritance for the people you love
Life Insurance+ isn’t a policy you can cash in, so you don’t get any money back if you cancel it, and if you stop paying your premiums you’re no longer covered.
The other policies work differently. Critical Illness+ pays out if you’re diagnosed with one of its listed critical illnesses and doesn’t pay out if you die. Income Protection+ pays a monthly income if illness or injury means you can’t work. Whole of Life Insurance+ has no set term and pays a lump sum whenever you die.
NFU Mutual life insurance policy options
NFU Mutual sells four Aviva policies, with advice or through its non-advised phone service: Term Assurance (Aviva Life Insurance+), Critical Illness Cover (Aviva Critical Illness+), Income Protection (Aviva Income Protection+) and Whole of Life Cover (Aviva Whole of Life Insurance+). It also offers business protection, such as Relevant Life Insurance.
-
Level termWith Life Insurance+ level cover, the lump sum stays the same throughout the policy term.
-
Decreasing termThe cover goes down every month at a rate set when you apply, usually to roughly keep track with a repayment mortgage.
-
Family incomeInstead of a lump sum, Life Insurance+ can pay equal monthly amounts until the end of the policy term.
-
Critical illnessCritical Illness+ covers 33 conditions, two additional conditions and children’s benefit as standard. It doesn’t pay out on death.
-
Income protectionIncome Protection+ pays a monthly income if you can’t work because of illness or injury, after a deferred period of 4 to 104 weeks.
-
Whole of lifeWhole of Life Insurance+ pays a lump sum whenever you die, with guaranteed premiums unless you choose increasing cover.
Term Assurance (Aviva Life Insurance+)
You choose level cover, decreasing cover or family income cover. Level cover pays a lump sum that stays the same, decreasing cover goes down every month at a rate set when you apply, and family income cover pays equal monthly amounts until the end of the term. You can add fixed increasing cover, of 3% or 5% a year, to level or family income cover, or index-linked increasing cover, in line with the Retail Prices Index (RPI) up to 10% a year, to level cover.
NFU Mutual says terms run from 1 to 50 years and the policy can be taken out from 18 to 89, with a minimum cover of £50,000 from age 78; it must end before your 91st birthday. Aviva’s policy summary says the term can be set in whole years or to a specific age, and gives a maximum starting age of 77 for life-only cover below £50,000, and 64 for life and critical illness cover, which must end by 75 with guaranteed premiums or 90 with reviewable premiums. You and the person covered must be in the UK, the Channel Islands, the Isle of Man or Gibraltar, with a legal right to live there.
Life cover has guaranteed premiums. With life and critical illness cover you can choose guaranteed or reviewable premiums; reviewable premiums are reviewed every five years and are only offered monthly. Life and critical illness cover includes 32 critical illness conditions, two additional conditions and children’s benefit as standard, and pays the full cover amount if you survive at least 10 days after diagnosis.
Depending on the definition, a critical illness may pay on diagnosis, once it reaches a specified severity or when named treatments or surgeries are carried out, and the definitions limit the cover: for example, some types of cancer aren’t covered. With level or decreasing cover, a claim for one of the two additional conditions, less advanced breast or prostate cancer, pays £25,000 or 25% of your cover, whichever is lower, and the policy carries on.
Critical Illness Cover (Aviva Critical Illness+)
Critical Illness+ pays a lump sum or a monthly amount if you’re diagnosed with one of its listed critical illnesses during the term and survive at least 10 days, and it doesn’t pay out if you die. It covers 33 critical illness conditions, two additional conditions and children’s benefit as standard, for one person or two, and the cover can stay the same, increase or decrease over the term.
You can apply from age 18. With guaranteed premiums the maximum age to apply is 64 and the cover must end by 75; with reviewable premiums it can run to 90. Terms run from 5 to 50 years.
Income Protection (Aviva Income Protection+)
Income Protection+ pays a monthly benefit if you can’t work because of illness or injury. You choose a deferred period of 4, 8, 13, 26, 52 or 104 weeks, and whether the benefit is paid for as long as you can’t work (full cover to term) or for up to 24 months per claim (limited payment term). There’s no limit on the number of claims, and benefit is paid monthly in arrears, starting a month after the deferred period ends.
The most you can insure is 65% of the first £60,000 you earn plus 45% of earnings above that, up to £240,000 a year. You need to be 18 to 59, working as an employee or self-employed, and to have worked for at least the last 12 months. Policies run for 5 to 52 years, can’t end before you’re 50 and must end before your 71st birthday. State benefits and investment income aren’t taken off your benefit, and under Aviva’s benefit guarantee your benefit won’t necessarily fall if your salary goes down after you take out the policy.
Waiver of premium, hospital benefit, trauma benefit and back to work benefit are included at no extra cost, and you can choose guaranteed or reviewable premiums. A longer deferred period means a cheaper premium but a longer wait for the benefit. Aviva has special arrangements for doctors, surgeons, nurses and midwives employed directly by the NHS: with a 52-week deferred period, they start getting some benefit as soon as their NHS sick pay goes down. If you can’t work, Aviva asks you to tell it before you’ve been off for two months, or one month with a 4-week deferred period.
Whole of Life Cover (Aviva Whole of Life Insurance+)
Whole of Life Insurance+ pays a lump sum when you die, whenever that is, and NFU Mutual presents it as a way to leave a legacy or help your family pay an inheritance tax bill. You can apply from 18 to 85, or up to 64 if you add waiver of premium, for yourself or as a joint policy that pays on the first or second death; on a joint policy the maximum age applies to the older person.
Premiums are guaranteed unless you choose increasing cover or change the policy, and you pay them by direct debit, monthly or yearly. Increasing cover rises by 3% or 5% a year, or with RPI up to 10%, and premiums then rise by twice the percentage increase in cover. Because you pay premiums for as long as the cover lasts, the total you pay could be more than the payout.
Business protection
For businesses, NFU Mutual offers protection covers with Aviva Life & Pensions UK Limited, including Relevant Life Insurance, which pays a lump sum to an employee’s family if they die.
Older NFU Mutual policies
NFU Mutual still supports customers with life cover and protection policies it no longer sells. They include NFU Mutual Level Term Assurance, Mortgage Term Assurance (decreasing cover linked to a mortgage), Special Temporary Assurance, Convertible Term Assurance, which gives the option to take out a Whole of Life policy without further medical underwriting, and an NFU Mutual Whole of Life policy whose payout is a guaranteed amount plus any bonuses added. On its older critical illness policies, the conditions covered depend on when the policy was taken out and are set out in the policy documents. Policies bought before April 2016 are administered by NFU Mutual.
Life Insurance+ life cover vs life and critical illness cover
NFU Mutual’s Term Assurance can be life cover or life and critical illness cover. Both include terminal illness cover, but the age limits, premiums and extra benefits differ. Here’s how the two compare:
| Feature | Life cover | Life and critical illness cover |
|---|---|---|
| Maximum age to apply | 77 (under £50,000), 89 (£50,000 or more) | 64 |
| Cover must end by | Age 90 | 75 (guaranteed premiums) or 90 (reviewable) |
| Premiums | Guaranteed | Guaranteed or reviewable |
| Terminal illness cover | Included | Included |
| Critical illnesses covered | Not available | 32, plus 2 additional |
| Children’s benefit | Not available | Included |
| Joint cover paying after both claims | ✓ (level and increasing cover) | Not available |
| Total permanent disability or extra care cover | Not available | Optional |
From Aviva’s Life Insurance+ policy summary (AL50001, 02/2026), linked from NFU Mutual’s Term Assurance page.
NFU Mutual policies at a glance
The key limits for the four Aviva policies NFU Mutual sells. The cover you’re offered depends on your circumstances and Aviva’s assessment.
| Limit | Term Assurance | Critical Illness Cover | Income Protection | Whole of Life Cover |
|---|---|---|---|---|
| Aviva policy | Life Insurance+ | Critical Illness+ | Income Protection+ | Whole of Life Insurance+ |
| Age when you apply | 18–89 | 18–64 | 18–59 | 18–85 |
| Policy term | 1–50 years | 5–50 years | 5–52 years | Whole of life |
| Cover must end | Before your 91st birthday | By 75 or 90, depending on premiums | Before your 71st birthday | — |
| Premiums | Guaranteed, or reviewable with critical illness cover | Guaranteed or reviewable | Guaranteed or reviewable | Guaranteed, unless you choose increasing cover |
| Cooling-off period | 30 days | 30 days | 30 days | 30 days |
Limits from NFU Mutual’s product pages and the Aviva policy summaries they link to, checked 3 October 2026.
What affects the cost of NFU Mutual life insurance?
The price you’re offered depends on the cover you choose and your circumstances. For Life Insurance+, Aviva’s policy summary says your premiums depend on:
- The type of cover you choose
- How much cover you want
- Your age
- Your occupation
- Your health and lifestyle
- Whether you smoke
Life cover has guaranteed premiums. With life and critical illness cover you can choose reviewable premiums instead: Aviva reviews them every five years, looking at things like its claims experience, medical advances and changes in the law, not your age or health, and they’re only offered monthly.
Increasing cover costs more each year. With fixed increases on level cover, premiums go up by 4.5% or 7.5% a year, and with index-linked cover by 1.5 times the RPI increase, up to 15%. On Whole of Life Insurance+, which Aviva prices on your cover amount, age, job, health, lifestyle and smoking habits, premiums go up by twice the percentage increase in cover.
NFU Mutual doesn’t charge an advice fee on Aviva products, because Aviva pays it commission, and there’s no charge for the first meeting with an adviser. Its non-advised phone service has no advice charge either.
In general, cover costs less the younger and healthier you are when you take it out, and decreasing term costs less than level term. Adding critical illness cover increases the price. Comparing plans from several insurers is the simplest way to see what’s available for your circumstances.
NFU Mutual life insurance benefits & extras
Depending on the policy, you may be eligible for these benefits at no extra cost:
| Benefit | What it does | Available with |
|---|---|---|
| Terminal illness benefit | Pays the cover amount if you’re diagnosed with a terminal illness that meets Aviva’s definition and an attending consultant doesn’t expect you to live more than another 12 months. | Available with: Life Insurance+ life cover and life and critical illness cover |
| House purchase cover | Free life cover while you’re buying a home, from when you exchange contracts, for the lowest of the amount you’ve applied for, the price of the house or £500,000. It ends after 90 days, on completion or when the policy starts, whichever comes first. | Available with: Life Insurance+ with level or decreasing cover |
| Protection Promise | Free cover while Aviva needs more information to decide on your application. On Life Insurance+ it’s for customers under 55, isn’t offered if you’re applying for the same cover from another insurer, lasts at most 90 days and pays up to £1,500,000 for level and decreasing cover. On Whole of Life Insurance+ it pays up to £500,000. | Available with: Life Insurance+, Whole of Life Insurance+ |
| Life change benefit | Increase your cover without extra health and lifestyle questions after events such as getting married or entering a civil partnership, becoming a parent or taking out a new mortgage. | Available with: Life Insurance+, Critical Illness+, Income Protection+, Whole of Life Insurance+ |
| Separation benefit | Split a joint policy into new single policies without extra health and lifestyle questions if you separate or rearrange your mortgage into one name. On Life Insurance+ it can’t be used once the policy is under trust. | Available with: Joint Life Insurance+, Critical Illness+ and Whole of Life Insurance+ policies |
| Inheritance tax benefit | Increase your cover without extra health questions if inheritance tax rules change. On Whole of Life Insurance+, the new cover amount can be the lowest of the rise in your potential inheritance tax bill, £1,000,000 or your original cover amount. | Available with: Life Insurance+ life cover on a level or decreasing basis, Whole of Life Insurance+ |
| Gift inter vivos benefit | Lets you exchange some or all of your cover to help pay a possible inheritance tax bill on gifts you’ve made in your lifetime. | Available with: Life Insurance+ joint life second event policies |
| Children’s benefit | With life and critical illness cover, your children are covered from 30 days old to their 18th birthday (21st in full-time education): £25,000 or 50% of your cover, whichever is lower, for a covered critical illness, £100 a night from the eighth night in hospital for up to 30 nights, and £5,000 if a child dies. | Available with: Life Insurance+ life and critical illness cover, Critical Illness+ |
| Income Protection+ extras | Aviva pays your premiums during a successful claim, after 13 weeks or from the end of your deferred period, whichever is sooner. The policy also pays £100 a night in hospital for up to 90 nights, a one-off trauma payment of six times your monthly benefit or £40,000, whichever is lower, for one of six listed traumatic events, and a back to work benefit if you can still work but earn less. | Available with: Income Protection+ |
You can also pay more to add extra benefits, including:
| Optional extra | What it does |
|---|---|
| Waiver of premium | Aviva pays your premiums if you can’t work because you’re ill or injured, after a deferred period of one, three or six months. On Life Insurance+ it can be added up to age 64; on Whole of Life Insurance+ it lowers the maximum age to apply to 64 and ends when the life covered reaches 71. |
| Upgraded critical illness | Adds 15 more critical illnesses that pay the full cover amount, £100 a night from the eighth consecutive night in hospital, £5,000 for each pregnancy affected by a listed complication, and upgraded additional critical illnesses that pay £30,000 or 100% of your cover, whichever is lower. |
| Upgraded children’s benefit | Replaces the standard children’s benefit and covers your children from birth until their 22nd birthday. |
| Fracture cover | A lump sum for one of 18 specified fractures, with at most one claim in any 12 months and nothing for a fracture in the first 7 days. Fractures during activities such as horse riding, rugby, boxing or martial arts, mountain biking and motor cycle sport aren’t covered. |
| Global treatment | Access to medical treatment abroad if you or your child is diagnosed with a serious illness or needs a medical procedure specified in the policy conditions, with a concierge service that recommends doctors and treatment centres, provided with Further. It pays up to £1 million per person in each 12-month period and £2 million in total, and renews every three years, so its premium might change then. |
| Total permanent disability | Pays your full cover amount if an illness or injury means you can never again do your own occupation, or at least three listed work-related tasks. Only available with life and critical illness cover. |
| Extra care cover | Pays your full cover amount plus £50,000 if, for example, you’re under 55 when you’re diagnosed with dementia, kidney failure, liver failure, Parkinson’s disease, motor neurone disease or respiratory failure as Aviva defines them. Only available with life and critical illness cover. |
Writing an NFU Mutual policy in trust
Aviva’s policy summaries say that if the payout goes to your estate it could be subject to inheritance tax, unless it’s left to a spouse or civil partner or you put the policy in a suitable trust. With a policy held under trust, the payout goes to the trustees, who pass it on to the beneficiaries you’ve chosen. Aviva describes trusts as a way to get the money to the right people at the right time and tax efficiently.
NFU Mutual’s financial advisers can advise on inheritance tax planning, including having life cover written in trust, and NFU Mutual can send existing customers a copy of any trust deed it holds for their plan.
A trust affects some benefits: the Life Insurance+ separation benefit can’t be used once the policy is under trust, and global treatment and fracture cover can’t be gifted under trust.
Read how trusts work, and what other insurers offer, in our guide to life insurance in trust.
Does NFU Mutual pay out?
NFU Mutual’s own published claims figure, 96% for 2025, is for General Insurance claims, not life cover. Its life policies are provided by Aviva, which has published its individual protection claims figures for 2025. Aviva’s 2025 figures combine Aviva’s own policies with Aviva Protection UK (formerly AIG Life) policies, and the life figures include Over 50s plans and terminal illness payments. For 2025, Aviva reported:
- Aviva life and terminal illness claims accepted
- 98.7%
- Aviva critical illness claims paid
- 90.7%
- Aviva income protection claims accepted
- 90%
- Paid by Aviva in life and terminal illness claims
- £860.7m
Source: Aviva’s published individual protection claims figures for 2025, covering all Aviva and Aviva Protection UK policies, not only those sold through NFU Mutual. Critical illness figures include children’s benefit and total permanent disability.
Across all individual protection policies, Aviva paid more than 51,000 claims totalling over £1.3 billion in 2025, accepting 96.9% of the claims it received. That included 40,277 life and terminal illness claims worth £860,665,410, £388,556,567 across 5,586 critical illness, children’s benefit and total permanent disability claims, and just over £63.5 million in income protection benefits to around 4,100 claimants.
Aviva says misrepresentation of health and lifestyle information was the leading reason it declined life claims, and most critical illness claims it couldn’t pay were because the diagnosis didn’t meet the policy definition.
Answering every question fully and honestly when you apply helps make sure your policy pays out when it’s needed.
How to make an NFU Mutual life insurance claim
Who you contact depends on when the policy was bought. NFU Mutual says policies bought before April 2016 are administered by NFU Mutual, policies bought between 1 August 2016 and 9 November 2025 by Aviva Protection UK Limited (formerly AIG), and policies bought after 9 November 2025 by Aviva Life & Pensions UK Limited. It helps to have the full name, the plan or policy number, the date of death or diagnosis and, for a critical illness claim, the medical condition.
For a policy administered by NFU Mutual, the person claiming should contact NFU Mutual as soon as possible: by phone on 0800 622 323 (Monday to Friday, 9am to 5pm), by post to Financial Services, NFU Mutual, Tiddington Road, Stratford-upon-Avon, Warwickshire, CV37 7BJ, or by email to Life_Claims_Mailbox@nfumutual.co.uk to report a death or Life_CIC_Mailbox@nfumutual.co.uk for a critical illness claim. NFU Mutual also has an online form for reporting a death, after which its claims team gets in touch to explain what happens next.
For policies bought between 1 August 2016 and 9 November 2025, NFU Mutual gives the Aviva Protection UK claims line, 0345 600 6815, and claimsteam@protection.aviva.com. Aviva Protection UK’s business moved to Aviva Life & Pensions UK Limited on 31 December 2025, and Aviva’s own claims pages now describe these as policies through Aviva Life & Pensions UK Limited. They give the same number for death, critical or terminal illness and income protection claims, open Monday to Thursday 8:30am to 6pm and Friday 8:30am to 5:30pm (0044 1737 441 815 from overseas). Their policy numbers are usually a ‘P’ followed by nine numbers, and they can’t be viewed on MyAviva.
For policies bought after 9 November 2025, you can start a claim online on Aviva’s website, or call 0800 158 3105 for income protection claims and 0800 015 1142 for all other claims (Monday to Friday, 8am to 6pm; +44 1603 603 277 from outside the UK).
- NFU Mutual policies, bought before April 2016 (Mon–Fri, 9am–5pm)
- 0800 622 323
- Policies bought 1 Aug 2016–9 Nov 2025, former Aviva Protection UK (AIG) policies (Mon–Thu 8:30am–6pm, Fri 8:30am–5:30pm)
- 0345 600 6815
- Former Aviva Protection UK (AIG) policies, claims from overseas
- 0044 1737 441 815
- Aviva policies bought after 9 Nov 2025 (Mon–Fri, 8am–6pm)
- 0800 015 1142
- Income protection claims, policies bought after 9 Nov 2025
- 0800 158 3105
- Aviva claims from outside the UK
- +44 1603 603 277
- Start a claim online (Aviva)
- aviva.co.uk (opens in a new tab)
- Claims guidance
- nfumutual.co.uk (opens in a new tab)
Key policy terms
A few terms that are worth knowing before you apply. Most come from Aviva’s policy summaries and conditions, which NFU Mutual links from its product pages; always check the documents for the exact policy you’re offered.
| Term | NFU Mutual policies |
|---|---|
| Cooling-off period | 30 days, with a refund of any premiums paid, on all four policies |
| Cancelling later | You can cancel at any time, but premiums already paid aren’t refunded, on all four policies |
| Suicide exclusion | First 12 months on Life Insurance+ and Whole of Life Insurance+ |
| Terminal illness | Included on Life Insurance+: claim if an attending consultant doesn’t expect you to live more than 12 months |
| Missed premiums | Life Insurance+: 60 days from each due date to pay |
| Changing your policy | Life Insurance+: from six months after the start, you can remove options and change the term or cover amount |
| Health questions | Answer them fully, truthfully and accurately, or Aviva may amend or cancel the policy or not pay a claim |
| Where you live | In the UK, the Channel Islands, the Isle of Man or Gibraltar, with a legal right to live there |
| Tax | Payouts are free of UK income tax and capital gains tax, but may be subject to inheritance tax unless the policy is in a suitable trust |
| Cash-in value | None on any of the four policies |
| FSCS protection | Life Insurance+ is covered, and the scheme may pay 100% of a successful claim if Aviva can’t |
| Complaints | Advice and NFU Mutual policies: NFU Mutual on 0800 622 323, with updates at 4 and 8 weeks if it takes longer. Aviva policies: Aviva on 0800 285 1098, with a written response within eight weeks. Then the Financial Ombudsman Service |
Is NFU Mutual life insurance good?
NFU Mutual is a long-established mutual, founded in 1910 and owned by its members, but for life cover it acts as the adviser rather than the insurer: the policies it sells are Aviva’s Life Insurance+, Critical Illness+, Income Protection+ and Whole of Life Insurance+. Defaqto rates the first three 5 stars and Whole of Life Insurance+ 4 stars, and Life Insurance+ comes with terminal illness cover, free house purchase cover and Aviva’s Protection Promise.
The trade-offs are that you set up cover through NFU Mutual’s advisers or its non-advised phone team, and its advice is restricted to products from a limited number of companies. There’s no over 50s plan in its current range, none of the four policies has a cash-in value, and reviewable premiums on life and critical illness cover are reviewed every five years. Older policies sit with different administrators depending on when they were bought, so it’s worth checking who looks after yours.
The right insurer for you depends on your needs and the price you’re offered, so it’s worth comparing NFU Mutual with other insurers.
Pros
- Policies provided by Aviva, with Life Insurance+, Critical Illness+ and Income Protection+ rated 5 stars by Defaqto
- Advice from NFU Mutual’s own Financial Advisers, with no advice fee on Aviva products
- Terminal illness cover and free house purchase cover on Life Insurance+
- Life cover can be taken out up to age 89, with at least £50,000 of cover
- Aviva accepted 98.7% of individual life claims in 2025
- Trustpilot score of 4.0 out of 5 across NFU Mutual’s products
Cons
- Cover is set up through an NFU Mutual adviser or its non-advised phone service
- Restricted advice, on products from a limited number of companies
- No over 50s plan in the current range
- No cash-in value on any of the four policies
- Reviewable premiums on life and critical illness cover are reviewed every five years
- Whole of Life Insurance+ is rated 4 stars by Defaqto, and you could pay in more than it pays out
- Older policies have different administrators depending on when they were bought
NFU Mutual life insurance policy documents
Before you take out a policy, it’s worth reading the policy summary and policy conditions for the exact product you’re offered. NFU Mutual links these Aviva documents from its product pages.
-
Life Insurance+ policy summary (AL50001) (opens in a new tab)
Term Assurance: cover types, included benefits, extras you can add and the age limits.
-
Life Insurance+ policy conditions (AL50002) (opens in a new tab)
The full terms of the Life Insurance+ contract with Aviva Life & Pensions UK Limited.
-
Critical Illness+ policy summary (AL51001) (opens in a new tab)
The conditions covered, children’s benefit, premiums and the age limits.
-
Critical Illness+ policy conditions (AL51002) (opens in a new tab)
The full terms of Critical Illness+, including the definitions of each condition.
-
Income Protection+ policy summary (AL52001) (opens in a new tab)
How much benefit you can get, deferred periods, included benefits and when payments stop.
-
Income Protection+ policy conditions (AL52002) (opens in a new tab)
The full terms of Income Protection+, including how incapacity is assessed.
-
Whole of Life Insurance+ policy summary (AL50007) (opens in a new tab)
How Whole of Life Insurance+ works, including increasing cover, premiums and the extra benefits.
-
Whole of Life Insurance+ policy conditions (AL50008) (opens in a new tab)
The full terms of Whole of Life Insurance+, from Aviva’s document library.
-
NFU Mutual Financial Planning Terms of Business (opens in a new tab)
NFU Mutual’s advised, non-advised and direct services, how it’s paid and who it acts for.
Documents are published by NFU Mutual and Aviva. NFU Mutual’s Whole of Life Cover page links to the Life Insurance+ policy conditions, so the Whole of Life Insurance+ conditions above are from Aviva’s website. The documents may be updated — the version you receive with your policy is the one that applies.
NFU Mutual life insurance FAQs
Aviva Life & Pensions UK Limited. NFU Mutual says its range of life cover and protection products is provided by Aviva Life & Pensions UK Limited, and its Term Assurance, Critical Illness Cover, Income Protection and Whole of Life Cover are Aviva’s Life Insurance+, Critical Illness+, Income Protection+ and Whole of Life Insurance+. See our Aviva review.
NFU Mutual says Term Assurance (Aviva Life Insurance+) can be taken out from 18 to 89, with a minimum cover of £50,000 from age 78, and it must end before your 91st birthday. With critical illness cover added, the maximum age to apply is 64. Whole of Life Insurance+ is available from 18 to 85.
NFU Mutual’s list of policies currently available to open is Income Protection, Term Assurance, Critical Illness Cover, Whole of Life Cover and Business Protection, so its current range has no over 50s plan. Whole of Life Cover can be taken out up to age 85, but you answer health and lifestyle questions when you apply.
NFU Mutual’s own 96% figure for 2025 is for General Insurance claims. For the life cover it sells, Aviva reported accepting 98.7% of individual life and terminal illness claims in 2025, paying 40,277 claims worth £860,665,410. These figures cover all Aviva and Aviva Protection UK policies, not only those sold through NFU Mutual.
It depends on when the policy was bought: call NFU Mutual on 0800 622 323 for policies bought before April 2016, 0345 600 6815 for policies bought between 1 August 2016 and 9 November 2025 (former Aviva Protection UK policies, now with Aviva), and Aviva on 0800 015 1142 (or 0800 158 3105 for income protection) for policies bought after 9 November 2025.
When you apply for cover you will be asked questions about your health and lifestyle, and based on this and the amount of cover requested, the insurer will decide if a medical is required or not.
Aviva’s policy summary says you need to answer the health and lifestyle questions fully, truthfully and accurately; if you don’t, Aviva may amend or cancel your policy, or may not pay a claim.
NFU Mutual says no advice fee or minimum fee is payable on Aviva products, because Aviva pays it commission to cover the cost of its services. There may be a charge for its advised service, but not for the initial meeting, and there’s no advice charge for its non-advised service.
Yes. Aviva’s policy summaries say a payout to your estate could be subject to inheritance tax unless you put the policy in a suitable trust, and with a trust the payout goes to the trustees. NFU Mutual’s financial advisers can advise on having life cover written in trust.
NFU Mutual’s Term Assurance can be set up with decreasing cover, which goes down each month and can be used to cover a capital and interest repayment mortgage. Free house purchase cover is included on level or decreasing cover while you buy a home. NFU Mutual’s older Mortgage Term Assurance can no longer be opened.
Yes. Life Insurance+ can cover two people, who can have different cover; it pays out on the first claim, or you can choose life cover that only pays once both people have claimed. Whole of Life Insurance+ can pay on the first or second death, and Critical Illness+ can also cover two people. If you separate, the separation benefit lets you split a joint policy into single policies without extra health questions.
Yes. All four Aviva policies give you 30 days to cancel and get back any premiums you’ve paid. You can cancel later, but premiums aren’t refunded, and none of the policies has a cash-in value.
Life Insurance+ and Whole of Life Insurance+ don’t pay out if the person covered dies from suicide or intentional self-inflicted injury in the first 12 months of the policy.
If you're struggling or thinking about suicide, our guide to suicide and life insurance lists where to get support straight away.
NFU Mutual still supports customers with policies it no longer sells. For a policy held with NFU Mutual, its Customer Enquiry Team is on 0800 622 323 (option 1), or you can use its web form or email customermail@nfumutual.co.uk. Its list of closed policies isn’t complete, so get in touch if you can’t find yours.
For changes to a policy administered by Aviva, NFU Mutual gives 0330 123 4467 for policies bought between 1 August 2016 and 9 November 2025, whose Cover Details document lists the changes you can make, and 0800 068 6800 for policies bought after 9 November 2025. Aviva, which now looks after policies issued by Aviva Protection UK or AIG Life, gives its own customer service line for them as 0345 600 6820 (email enquiries@protection.aviva.com), and its complaints line for them is 0345 600 6813.
Sources
The facts on this page come from these sources.
- Wikimedia Commons — Wikimedia Commons file page - NFU Mutual Headquarters, Tiddington - geograph.org.uk - 1727835.jpg (photo, CC BY-SA 2.0) (opens in a new tab), commons.wikimedia.org, accessed 3 October 2026.
- Companies House — Companies House - NATIONAL FARMERS UNION MUTUAL INSURANCE SOCIETY LIMITED(THE) (00111982) (opens in a new tab), find-and-update.company-information.service.gov.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual The power of mutuality (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual How to set up a life cover or protection policy (advised and non-advised) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Annual Report & Accounts 2025 (excerpt: business model and Life, Pensions and Investments) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Term Assurance page (Aviva Life Insurance+) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Other life cover and protection (policies no longer available to open) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual (document by Aviva Life & Pensions UK Limited) — Aviva Life Insurance+ policy summary (AL50001 02/2026), linked from NFU Mutual Term Assurance page (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Critical Illness Cover page (Aviva Critical Illness+) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Income Protection page (Aviva Income Protection+) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Whole of Life Cover page (Aviva Whole of Life Insurance+) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Business Protection page (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Financial Planning Terms of Business (TOB-COM-1125, NFU Mutual Select Investments Limited) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- Defaqto — Defaqto Star Ratings (Life & Protection) for the Aviva products NFU Mutual sells (opens in a new tab), defaqto.com, accessed 24 September 2026.
- Trustpilot — Trustpilot - NFU Mutual (www.nfumutual.co.uk) company reviews, all products (opens in a new tab), uk.trustpilot.com, accessed 3 October 2026.
- Aviva plc — Aviva paid nearly £2 billion in protection claims in 2025 (Aviva claims statistics 2025) (opens in a new tab), aviva.com, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Let's talk about Life Cover and Protection (contact, changes and claims by administrator) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- Financial Conduct Authority — FCA Financial Services Register - The National Farmers Union Mutual Insurance Society Limited (FRN 117664) (opens in a new tab), register.fca.org.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Life Cover and Protection (product overview page) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Our awards and industry ratings (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Bereavement claims: notify us of a death (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- Companies House — Companies House - NFU MUTUAL SELECT INVESTMENTS LIMITED (08049488) (opens in a new tab), find-and-update.company-information.service.gov.uk, accessed 3 October 2026.
- Companies House — Companies House - AVIVA PROTECTION UK LIMITED (06367921), formerly AIG Life Limited (opens in a new tab), find-and-update.company-information.service.gov.uk, accessed 3 October 2026.
- Aviva Protection UK Limited (filed at Companies House) — Aviva Protection UK Limited (formerly AIG Life Limited) full accounts for the year ended 31 December 2025, filed at Companies House (scanned PDF, text by OCR): Part VII transfer to Aviva Life & Pensions UK Limited (opens in a new tab), find-and-update.company-information.service.gov.uk, accessed 3 October 2026.
- NFU Mutual (document by Aviva Life & Pensions UK Limited) — Aviva Life Insurance+ policy conditions (AL50002), linked from NFU Mutual Term Assurance and Whole of Life pages (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- The Gazette — The Gazette notice 4930819 - Part VII transfer of Aviva Protection UK Limited (formerly AIG Life Limited) to Aviva Life & Pensions UK Limited (opens in a new tab), thegazette.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Legal Policy (who we are, UK only) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Financial Services Compensation Scheme page (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- Smart Money People — Smart Money People - NFU Mutual reviews (all products) (opens in a new tab), smartmoneypeople.com, accessed 3 October 2026.
- Fairer Finance — Fairer Finance - life insurance customer experience ratings (NFU Mutual, Autumn 2026) (opens in a new tab), fairerfinance.com, accessed 3 October 2026.
- NFU Mutual (document by Aviva Life & Pensions UK Limited) — Aviva Critical Illness+ policy summary (AL51001 04/2025), linked from NFU Mutual Critical Illness Cover page (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual (document by Aviva Life & Pensions UK Limited) — Aviva Whole of Life Insurance+ policy summary (AL50007 02/2026), linked from NFU Mutual Whole of Life Cover page (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual (document by Aviva Life & Pensions UK Limited) — Aviva Income Protection+ policy summary (AL52001 10/2024), linked from NFU Mutual Income Protection page (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Inheritance Tax Planning page (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Trust information request (existing plans) (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Life Cover and Protection Claims (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
- Aviva — Aviva - Make a claim on a policy through Aviva Life & Pensions UK Limited issued by Aviva Protection UK Limited or AIG Life Limited (claims hub) (opens in a new tab), aviva.co.uk, accessed 3 October 2026.
- Aviva — Aviva - Death claim for policies issued by Aviva Protection UK Limited or AIG Life Limited (phone, hours, email) (opens in a new tab), aviva.co.uk, accessed 3 October 2026.
- Aviva — Aviva - Critical or terminal illness claim for policies issued by Aviva Protection UK Limited or AIG Life Limited (phone, hours, email) (opens in a new tab), aviva.co.uk, accessed 3 October 2026.
- Aviva — Aviva - Income protection claim for policies issued by Aviva Protection UK Limited or AIG Life Limited (phone, hours, email) (opens in a new tab), aviva.co.uk, accessed 3 October 2026.
- Aviva — Aviva - AIG Life Insurance contact us (policies issued by Aviva Protection UK Limited or AIG Life Limited) (opens in a new tab), aviva.co.uk, accessed 3 October 2026.
- NFU Mutual — NFU Mutual Complaints (opens in a new tab), nfumutual.co.uk, accessed 3 October 2026.
Related pages
-
Best life insurance
What to compare when you choose a policy.
-
Term life insurance
Cover for a set number of years, with level or decreasing cover.
-
Decreasing term life insurance
The payout falls over the term, often in line with a mortgage.
-
Mortgage life insurance
Match your cover to your mortgage and protect your home.
-
Whole of life insurance
Lifelong cover and how it differs from term cover.
-
Joint life insurance
One policy for two people, compared with two single policies.