Santander life insurance review 2026
A look at Santander’s life insurance policies, provided by Aviva, with their included benefits, claims record and independent ratings.
- Trustpilot
- 3.6 / 5
- 12,642 reviews · whole bank
- Defaqto
- 3 out of 5 stars
- Level term
- Life claims paid
- 98.7%
- Aviva, 2025
- Entry age
- 18–77
- Life Insurance Plan, 1–50 year terms
In a nutshell
Santander is a UK bank, part of Banco Santander, that sells life insurance, critical illness cover and over 50s life insurance provided, underwritten and administered by Aviva. You can buy them online or by phone. Santander gives you information to help you decide, but not advice.
- The Life Insurance Plan offers level, decreasing or increasing cover for one person or two, with terminal illness cover included, for ages 18–77 over 1–50 years.
- The Critical Illness Plan is a separate policy for ages 18–64 over 5–50 years. It pays out if you’re diagnosed with a covered illness, not on death, and includes children’s benefit.
- Over 50s Life Insurance has guaranteed acceptance for ages 50–80 and doesn’t ask about your health. Premiums are £5 to £100 a month and stay the same.
- Defaqto rates Over 50s Life Insurance 5 stars and the Life Insurance Plan and Critical Illness Plan 3 stars. Santander as a whole scores 3.6 out of 5 on Trustpilot.
- Aviva reported paying 98.7% of individual life claims and 90.7% of critical illness, children’s benefit and total and permanent disability claims in 2025. These figures cover all Aviva individual protection policies, not only Santander’s.
- When we checked on 25 September 2026, Santander offered £100 cashback on a new policy, or £150 for Santander mortgage, Private Banking, Select and Santander Edge current account customers. Eligibility rules and a 24-month minimum term apply.
Who are Santander?
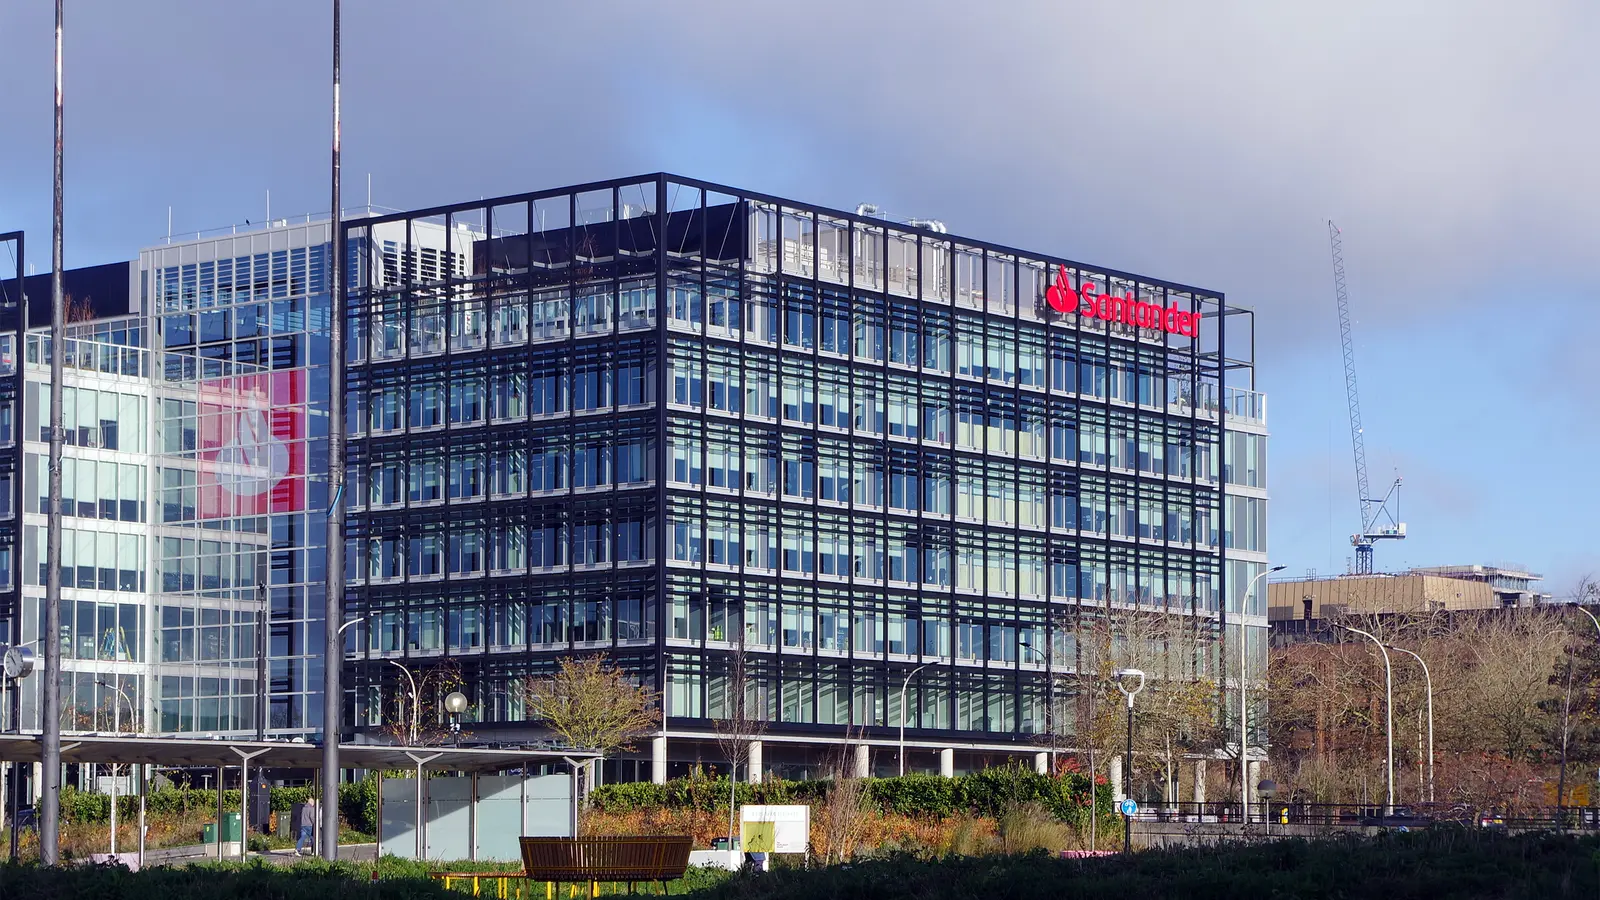
Santander UK is a bank in the Banco Santander group, which was founded in 1857 and has a presence in Europe and America. Its UK roots go back to 1849 and the National Freehold Land and Building Society. Santander launched in the UK in 2010, when Abbey, Alliance & Leicester and Bradford & Bingley were rebranded. Its UK headquarters is Unity Place in Milton Keynes.
- Bank
- Santander UK plc
- Registered in England and Wales
- No. 02294747
- Registered office
- 2 Triton Square, Regent’s Place, London, NW1 3AN
- FCA / PRA register number
- 106054
- Life insurer
- Aviva Life & Pensions UK Limited
- Insurer’s FCA / PRA number
- 185896
- Group
- Banco Santander
Santander doesn’t underwrite life insurance itself. It acts as an insurance intermediary and can only offer life and critical illness insurance from Aviva. Aviva Life & Pensions UK Limited provides, underwrites and administers the Life Insurance Plan, Critical Illness Plan and Over 50s Life Insurance.
Santander and Aviva first announced their partnership in 2011. On 5 March 2020 they agreed to continue it, with a six-year life insurance partnership running to December 2026.
-
1849
National Freehold Land and Building Society established
-
1944
Abbey National Building Society formed by the merger of the Abbey Road and National building societies
-
1989
Abbey National becomes the first UK building society to demutualise and lists on the London Stock Exchange
-
2004
Banco Santander acquires Abbey National plc
-
2010
Abbey, Alliance & Leicester and Bradford & Bingley rebranded as Santander UK
-
2011
Santander and Aviva first announce their partnership
-
2020
Santander and Aviva renew their partnership, with life insurance running to December 2026
-
2026
Santander UK completes its £2.65 billion acquisition of TSB
With a new policy, you apply through Santander, but the policy is Aviva’s. Aviva handles the claims and publishes the claims figures.
Some older Santander policies come from other insurers. Life policies taken out before 30 June 2011 are underwritten by Royal London. Santander’s insurance support page also lists a SunLife Guaranteed Over 50 Plan, provided by SunLife.
On 30 April 2026 Santander UK completed its £2.65 billion acquisition of TSB. Santander says the two banks together serve nearly 28 million retail and business customers. TSB continues to operate as a separate bank under its own brand for now.
Whether Santander is the right choice for you depends on the cover you need and the price you’re offered, so it’s worth comparing plans before you decide.
Compare quotes from a panel of UK insurers
- Quick 3 step process
- 60 second form
- Free quotes, no obligation
Santander life insurance ratings and reviews
Santander scores 3.6 out of 5 on Trustpilot, 3.87 out of 5 on Smart Money People and 78% overall for life insurance with Fairer Finance. Defaqto rates its Over 50s plan 5 stars and its term and critical illness plans 3 stars. The Trustpilot and company-wide Smart Money People scores cover the whole bank, not just life insurance.
| Review site | Rating | What it means |
|---|---|---|
| Trustpilot | 3.6 / 5 · Average | Based on 12,642 reviews of Santander as a whole, with 25% at 5 stars and 69% at 1 star. Santander invites customers to review it and has replied to 54% of negative reviews. View on Trustpilot (opens in a new tab) |
| Smart Money People | 3.87 / 5 · Good | Based on 2,662 reviews across Santander’s products. Its Santander Life Insurance page shows 4.17 from only 3 reviews (all 5-star), and one of those is about a children’s savings account. View on Smart Money People (opens in a new tab) |
| Defaqto | 3–5 stars | Defaqto rates each product from 1 to 5 stars. Santander’s Life Insurance Plan and Critical Illness Plan are rated 3 stars, and its Over 50s Life Insurance is rated 5 stars. View on Defaqto (opens in a new tab) |
| Fairer Finance | 78% overall | In Fairer Finance’s Autumn 2026 life insurance customer experience ratings, Santander scores 89% for claims, 91% for complaints and 54% for transparency. Fairer Finance also gives Santander Over 50s Life Assurance a 3-star product rating. View on Fairer Finance (opens in a new tab) |
Defaqto ratings for each Santander policy
Defaqto rates each product from 1 to 5 stars. It gives Santander’s Over 50s policy 5 stars and each of its four rated term life and standalone critical illness products 3 stars.
| Policy | Range | Defaqto rating |
|---|---|---|
| Level term life insurance | Life Insurance Plan | 3 out of 5 stars |
| Decreasing term life insurance | Life Insurance Plan Decreasing Cover | 3 out of 5 stars |
| Critical illness (standalone) | Critical Illness Plan (Level Or Increasing) | 3 out of 5 stars |
| Critical illness (standalone) | Critical Illness Plan Decreasing | 3 out of 5 stars |
| Over 50s life insurance | Over 50's Life Assurance | 5 out of 5 stars |
Ratings checked on 24 September 2026 and may have changed since. Defaqto ratings: defaqto.com (opens in a new tab)
Customer scores on Trustpilot and Smart Money People cover Santander’s products as a whole, and Smart Money People’s life insurance score rests on just three reviews. Fairer Finance’s ratings are for life insurance only. Claims on Aviva-provided policies go to Aviva, and its claims figures are below.
What does Santander life insurance cover?
Santander’s Life Insurance Plan pays a lump sum if you die during the policy term, or if you’re diagnosed with a terminal illness that meets Aviva’s definition. It pays out only once, and when a claim is paid the policy ends.
You can cover one person on a single policy or two people on a joint policy. A joint policy needs one monthly premium, but it pays out once and doesn’t cover the second person after the first person dies. Santander suggests separate single policies as an alternative, so the second person’s cover continues if Aviva pays out for the first.
You decide how much cover you need and how long the policy should last. The payout could help your loved ones with:
- Paying off a repayment or interest-only mortgage
- Supporting dependants for a set time, for example until a child reaches independence
- Household bills and everyday living costs
- Childcare, school or university costs
- Outstanding loans and credit cards
Santander’s Critical Illness Plan is a separate policy. It pays a lump sum if you’re diagnosed with a critical illness that meets the policy definition and survive for at least 10 days. It doesn’t pay out if you die.
Both policies pay the full cover amount only once, on a valid claim. They have no cash-in value at any time, and if your payments stop, your cover stops too.
Santander life insurance policy options
Santander sells three policies, all provided, underwritten and administered by Aviva: the Life Insurance Plan, the Critical Illness Plan and Over 50s Life Insurance. Within the Life Insurance Plan, you choose from three types of cover.
-
Level termThe cover amount stays the same throughout the term. Santander says it’s commonly used to protect an interest-only mortgage.
-
Decreasing termThe cover amount reduces each month, broadly in line with a repayment mortgage, using a fixed interest rate of 8%.
-
Increasing coverThe cover amount rises each year in line with the Consumer Prices Index, up to 10%, and premiums rise at 1.5 times that rate.
-
Critical illnessA separate policy that pays a lump sum if you’re diagnosed with a covered critical illness. Available as level, decreasing or increasing cover.
-
Over 50sWhole of life cover with guaranteed acceptance that doesn’t ask about your health. It pays a fixed lump sum on death after 12 months, or for accidental death in year one.
Life Insurance Plan
The Life Insurance Plan provides life cover and terminal illness cover, with three types of cover paid as a lump sum. Level cover stays the same throughout the policy term, which Santander says is commonly used for an interest-only mortgage. Decreasing cover goes down each month using a fixed 8% interest rate, broadly in line with a repayment loan.
Santander says decreasing cover should clear a repayment mortgage if all repayments are made, and is also used to protect dependants until a child is independent. Increasing cover rises each year in line with the Consumer Prices Index (CPI), up to a maximum of 10%.
Premiums for level and decreasing cover are guaranteed and stay the same unless you change the policy. With increasing cover, premiums go up each year at 1.5 times the CPI increase, capped at 15% a year. Aviva carries out each yearly increase without further health and lifestyle questions, and you can choose not to increase your cover.
You can apply aged 18 to 77 for a term of 1 to 50 full years, ending before the oldest person covered turns 91. On a joint policy, the maximum entry age applies to the oldest life covered. You must be in the UK with a legal right to live there and treat it as your main home, excluding the Channel Islands, Isle of Man and Gibraltar.
Critical Illness Plan
The Critical Illness Plan is a separate policy from the Life Insurance Plan and doesn’t pay out on death. It pays a cash lump sum if you’re diagnosed with a covered critical illness that meets Aviva’s definition and survive for at least 10 days. Covered conditions include cancer (excluding less advanced cases), heart attack, stroke, multiple sclerosis with symptoms, motor neurone disease with permanent symptoms, dementia of specified severity and terminal illness.
Some cancers aren’t covered, and certain illnesses require permanent symptoms to claim. An additional critical illness benefit pays the lower of £25,000 or 25% of your cover for breast carcinoma in situ (with surgery) or low-grade prostate cancer (with specified treatment). Other listed additional conditions pay the lower of £20,000 or 20%, and your policy continues afterwards.
You must be aged 18 to 64 to apply, for a term of 5 to 50 years ending before the oldest person covered turns 76. It can be a single or joint policy and pays out only once. On a joint policy, if one person dies, the policy continues for the survivor.
Over 50s Life Insurance
Over 50s Life Insurance is a single-life whole of life policy for people aged 50 to 80. Aviva guarantees to accept eligible applicants and doesn’t ask about your health. The over 50s section below covers its premiums, first-year rules and exclusions.
How to apply
Santander says you can get a quote on its website in minutes, or call its phone team on 0800 028 3744 (0800 085 0540 for Over 50s) for non-advised information. Santander doesn’t charge a fee for arranging a policy online: Aviva pays it commission, which is included in your premium and shown in your quote. If you came from a third-party website and take out a life policy, Santander pays that website.
Santander Life Insurance Plan vs Critical Illness Plan
The Life Insurance Plan and the Critical Illness Plan are separate policies: one pays out on death or terminal illness, the other on diagnosis of a covered critical illness.
| Feature | Life Insurance Plan | Critical Illness Plan |
|---|---|---|
| Pays out on death | Included | Not available |
| Terminal illness | Included | ✓ (a covered condition) |
| Age when you apply | 18–77 | 18–64 |
| Policy term | 1–50 years | 5–50 years |
| Cover must end | Before the oldest person covered turns 91 | Before the oldest person covered turns 76 |
| Level, decreasing or increasing cover | Included | Included |
| Guaranteed premiums (level or decreasing cover) | Included | Included |
| Single or joint | Both | Both |
| Separation benefit (joint policies) | Included | Included |
| Cooling-off period | 30 days | 30 days |
| Cash-in value | None | None |
From the Life Insurance Plan and Critical Illness Plan policy summaries and conditions, checked 25 September 2026.
Santander life insurance at a glance
The table sets out the main limits of Santander’s three Aviva-underwritten policies. On a joint Life Insurance Plan the maximum entry age applies to the older applicant, and on both term plans the maximum end age applies to the older person covered. Your premium depends on the cover you choose and your personal circumstances.
| Limit | Life Insurance Plan | Critical Illness Plan | Over 50s Life Insurance |
|---|---|---|---|
| Age when you apply | 18–77 | 18–64 | 50–80 |
| Policy term | 1–50 years | 5–50 years | Whole of life |
| Cover must end | Before age 91 | Before age 76 | Lasts for life |
| Single or joint | Both | Both | Single only |
| Premiums | Guaranteed on level and decreasing cover | Guaranteed on level and decreasing cover | Guaranteed, £5–£100 a month |
| Cooling-off period | 30 days | 30 days | 30 days |
| Cash-in value | None | None | None |
| Defaqto | 3 stars | 3 stars | 5 stars |
Limits from the Aviva policy documents for Santander’s policies, checked 25 September 2026.
What affects the cost of Santander life insurance?
The price you’re offered depends on your personal circumstances and the cover you choose. Aviva says premiums for the Life Insurance Plan and Critical Illness Plan depend on the type and amount of cover and on your personal circumstances, which could include:
- Your age
- Your health
- Your lifestyle
- Whether you smoke
- Your job
- Where you live
- The type of cover: level, decreasing or increasing
- How much cover you want
- How long you want cover for
Santander says the younger and healthier you are, the lower the cost of a life insurance policy. For Over 50s Life Insurance, your premium depends on the cover amount, your age and your smoking habits. Premiums are paid every month by Direct Debit.
In Aviva’s published examples, two people aged 30 and 32 pay £15 a month for £100,000 of increasing life cover over 20 years. After a 2.5% CPI rise, their new monthly premium is £15.56. For a Critical Illness Plan, Aviva’s example couple aged 30 and 32 pay £60 a month for £100,000 of increasing cover over 20 years.
Decreasing term cover generally costs less than level term because the payout reduces over time, and adding critical illness cover increases the price. Comparing quotes from several insurers is the simplest way to see what’s available for your circumstances.
Santander life insurance benefits & extras
Depending on whether you choose the Life Insurance Plan or the Critical Illness Plan, these benefits are included with your policy:
| Benefit | What it does | Available with |
|---|---|---|
| Terminal illness cover | Pays the cover amount if the person covered is diagnosed during the term with an incurable illness that their attending consultant expects to lead to death within 12 months. | Available with: Life Insurance Plan |
| House purchase cover | Free death cover while buying a house, from exchange of contracts (or completed missives) until completion, the policy start date or 90 days, whichever comes first. It pays the lowest of the amount applied for, the house price or £500,000, and excludes terminal illness. | Available with: Life Insurance Plan |
| Protection Promise | Free cover for up to 90 days while Aviva needs more information before deciding on your application. It pays the cover amount applied for, up to £500,000, unless death results from a pre-existing condition you knew about or had symptoms of. | Available with: Life Insurance Plan |
| Separation benefit | Lets you split a joint policy into single policies if you separate or move your mortgage into one name. Aviva says each new policy can keep up to the existing cover amount without further health and lifestyle questions. It applies only to policies accepted on standard terms (and not if a Life Insurance Plan is in trust). You can use it once from six months after the start, within 180 days of separating and before the eldest person covered turns 55. | Available with: Joint Life Insurance Plan and Critical Illness Plan policies |
| Additional critical illness benefit | Pays a smaller sum for listed additional conditions without ending your policy. It pays the lower of £25,000 or 25% of your cover for breast carcinoma in situ (with surgery) or low-grade prostate cancer (with specified treatment). Other listed conditions pay the lower of £20,000 or 20%, and each person covered can claim once per condition. | Available with: Critical Illness Plan |
| Children’s benefit | Pays the lower of £25,000 or 50% of your cover if a covered child is diagnosed with a listed illness and survives 10 days. It also pays £5,000 if a covered child dies during the policy term. It covers natural, step and legally adopted children aged 30 days to 18 (21 in full-time education), excluding conditions present at birth or with symptoms before cover began. | Available with: Critical Illness Plan |
Santander over 50s life insurance
Santander’s Over 50s Life Insurance, provided by Aviva, is a single-life whole of life policy for people aged 50 to 80. Aviva guarantees to accept eligible applicants and doesn’t ask about your health: you answer questions about your date of birth and whether you smoke. The policy lasts for the whole of your life as long as you pay your premiums when due.
When you apply, you choose either the monthly premium (£5 to £100) or the fixed lump sum to be paid out. Premiums are guaranteed to stay the same. You can hold more than one policy if your total monthly premiums across all your Aviva Over 50s policies taken out through Santander don’t exceed £100. You stop paying at the policy anniversary after your 90th birthday or after 30 years, whichever is earlier, and cover continues until a claim is paid.
Aviva guarantees to pay the cover amount if you die 12 months or more after taking out the policy. In the first year, the full lump sum is paid only for an accidental death; death from any other cause pays an amount equal to the premiums you’ve paid.
First-year accidental death cover excludes intentional self-inflicted injury (including suicide), alcohol or drug misuse, criminal acts, hazardous pursuits, and flying except as a paying passenger on a commercial airline. Aviva also won’t pay the cover amount for an accidental death in the first 12 months while you’re living outside the UK, Europe, the USA, Canada, Australia or New Zealand.
- Age to apply
- 50–80
- What you’re asked
- Your date of birth and whether you smoke, not about your health
- Monthly premium
- £5–£100
- Premiums stop
- Anniversary after 90th birthday, or after 30 years if sooner
- Full cover
- After 12 months
- Single or joint
- Single only
- Cash-in value
- None
- Defaqto
- 5 stars
- The lump sum is fixed, so inflation will reduce what it can buy in the future.
- Depending on how long you live, the lump sum paid out could be less than the total you’ve paid in premiums. Where it applies, your quote shows the age at which your premiums paid will equal the cover amount.
- You can’t change the policy once it has started, but you could take out another policy to top up your cover, subject to availability, eligibility and the premium limit.
- If you stop paying during the premium term, your policy and cover end 60 days after your last payment was due, with no money back.
- Only one person can be covered, but partners can each take out a policy.
- Aviva can’t give financial advice on this policy, and applying online or by phone is non-advised. For help with an application, call Santander’s phone team on 0800 085 0540.
- Santander says the lump sum can help towards funeral costs, and its Over 50s page offers a funeral cost estimator.
Compare other insurers’ over 50s plans in our guides to over 50s life insurance, guaranteed life insurance and over 60s life insurance.
Writing a Santander policy in trust
Santander says you can put your life insurance policy in trust so the proceeds don’t form part of your estate for inheritance tax purposes. Payouts on the Life Insurance Plan and Over 50s plan are currently free from UK income and capital gains tax. They may be subject to inheritance tax unless the policy is in a suitable trust.
Santander links to Aviva’s protection trust guide and trust forms, which can also be used for existing policies. In Aviva’s trust guide example, a claim on a policy in a Discretionary Gift Trust is paid to the surviving trustees as soon as it’s accepted, without waiting for probate.
The Aviva Survivor Trust is for Aviva joint life policies and lets trustees pay the surviving partner if they’re still alive 31 days after their partner’s death. The Aviva Discretionary Gift Trust works for single or joint policies and can include children or grandchildren born after the trust is set up. Aviva’s guide also describes the Aviva Bare Trust, where the beneficiaries and their shares can’t be changed once set up.
Aviva’s trust forms say a trust can’t be cancelled once it’s set up, and a joint Life Insurance Plan in trust can’t use the separation benefit. You also can’t put a policy in trust if you’ve assigned it to a lender, such as your mortgage provider, as security for a loan. Santander suggests seeking specialist legal advice if you’re unsure whether to put your policy in trust.
Read how trusts work, and what other insurers offer, in our guide to life insurance in trust.
Santander cashback offer
Note: Free gifts are offered by select brokers only, our life insurance brokers do not offer free gifts.
When we checked on 25 September 2026, Santander was offering £150 cashback to new or existing Santander mortgage, Private Banking, Select and Edge current account customers. Everyone else could get £100. It applies to one new Aviva-underwritten Life Insurance Plan, Critical Illness Plan or Over 50s policy sold by Santander UK plc. To receive £150, your qualifying Santander mortgage or account must still be open when the payment is processed; otherwise £100 is paid.
The policy term must be at least 24 months, and cashback is paid once per customer (to the first named policyholder on a joint policy). You’re not eligible if you cancelled a Santander life protection policy in the last 12 months, and it isn’t paid if a claim has been paid during the qualifying period.
Santander aims to pay the cashback 280 days after the policy start date, if the policy hasn’t been cancelled and your payments are up to date. It goes into your Santander current account, where it shows as ‘Ins Cashback’ with no separate notification; without one, you get a cheque. Extra checks on new policies can delay it. If it hasn’t arrived within 12 months of the start date, call the Santander helpline on 0800 234 6068.
The promotional period started on 1 August 2023, and Santander can withdraw the offer without notice at any time. Santander receives an annual amount from Aviva towards marketing, which can be used for promotional offers such as cashback.
See other insurers’ offers and their conditions in our guides to life insurance with a free gift and over 50 life insurance with a free gift.
Does Santander pay out?
Claims on Santander’s Aviva policies are handled by Aviva, which reported paying 98.7% of individual life claims and 90.7% of critical illness claims in 2025. Santander quotes that 98.7% on its pages. Aviva’s figures cover all its individual protection policies (including Aviva Protection UK, formerly AIG Life), not only Santander’s. For 2025, Aviva reported:
- Life claims paid
- 98.7%
- Critical illness claims paid
- 90.7%
- Paid in life claims
- £860.7m
Aviva claims paid by year
| Year | Life claims paid | Critical illness claims paid | Total paid (life) |
|---|---|---|---|
| 2025 | 98.7% | 90.7% | £860.7m |
| 2024 | 98.8% | 91.5% | £862.1m |
| 2023 | 99.3% | 91.6% | £761.7m |
Source: Aviva published claims statistics for 2023, 2024 and 2025. The figures cover all Aviva individual protection policies, not only those sold through Santander, and from 2024 they also include former AIG Life policies (now Aviva Protection UK), so 2023 isn’t directly comparable. Life figures include terminal illness; critical illness figures include children’s benefit and total and permanent disability.
In 2025 Aviva paid 40,277 individual life and terminal illness claims, a category that includes Over 50s plans. Across all individual protection claims, it paid more than 51,000 claims totalling over £1.3 billion, accepting 96.9% of all claims received.
The leading reason Aviva declined life claims in 2025 was misrepresentation of relevant information, particularly health and lifestyle details. Most critical illness claims it couldn’t pay were because the diagnosis didn’t meet the policy definition. On the Life Insurance Plan and Critical Illness Plan, you must answer all application questions completely, truthfully and accurately, or Aviva may reduce or refuse a claim.
How to make a Santander life insurance claim
To make a claim, contact the insurer shown in your policy documents: Aviva for policies taken after 30 June 2011, Royal London for older life policies, or SunLife for the SunLife Guaranteed Over 50 Plan. For Aviva policies, you can complete Aviva’s online claims notification form or call 0800 158 3467, Monday to Friday, 8am to 6pm. The Life Insurance Plan and Critical Illness Plan summaries also give Aviva’s UK life claims number, 0800 015 1142 (+44 1603 603 277 from abroad).
To start a life claim with Aviva, have these ready: the person’s name, your relationship to them, the cause of death, the policy number if you have it, and your contact details. Aviva may ask for a death certificate, proof of death or terminal illness, and proof of who legally owns the policy. If Aviva asks for information from third parties, it pays for it.
For life policies taken out before 30 June 2011, call Royal London on 0345 741 3002 (Monday to Friday, 8am to 6pm, excluding bank holidays). For the SunLife Guaranteed Over 50 Plan, call SunLife on 0800 008 6060 (Monday to Friday, 8am to 8pm). SunLife asks for items including the original death certificate and a copy of the policyholder’s will if there is one.
Santander’s bereavement page lists the pre- and post-30 June 2011 policy numbers the other way round from its insurance support page. Our table follows the support and product pages: 0800 141 3430 for Aviva policies (after 30 June 2011) and 0345 741 3002 for Royal London policies (before 30 June 2011). You can also tell Santander and other banks about a death at the same time through the Death Notification Service.
- Life claims (Aviva)
- 0800 158 3467
- Aviva life claims line
- 0800 015 1142
- Aviva claims lines open
- Mon–Fri, 8am–6pm
- Policy changes and documents
- 0800 141 3430
- Policies before 30 June 2011 (Royal London)
- 0345 741 3002
- SunLife Guaranteed Over 50 Plan
- 0800 008 6060
- Santander bereavement team
- 0800 587 5870
Key policy terms
The main terms of Santander’s policies are below. Always check the policy conditions for the exact product you’re offered.
| Term | Santander policies |
|---|---|
| Cooling-off period | 30 days, with a refund of any premiums paid |
| Cancelling later | You can still cancel, but premiums aren’t refunded |
| Missed payments | 60 days from each due date to pay; after that Aviva cancels the policy |
| Suicide exclusion | Life Insurance Plan: first 12 months. Over 50s: excluded from first-year accidental death cover |
| Terminal illness | Life Insurance Plan pays if an illness that can’t be cured is expected to lead to death within 12 months |
| Medical exam | Life Insurance Plan: Santander says you might need one, and it’s paid for. Over 50s: you’re asked your date of birth and whether you smoke, not about your health |
| Changing your policy | Life Insurance Plan: certain changes from six months after the start. Over 50s: can’t be changed once started |
| Write in trust | Yes — Santander links to Aviva trust forms |
| Cash-in value | None |
| Tax | Life Insurance Plan and Over 50s: currently free from UK income and capital gains tax; inheritance tax may apply unless the policy is in a suitable trust. Critical Illness Plan: currently normally free from UK income and capital gains tax |
| FSCS protection | The scheme may cover up to 100% of a successful claim if Aviva becomes insolvent |
| Payment difficulties | Existing Santander policyholders with Aviva-underwritten policies in short-term financial difficulty may be able to get help with monthly payments from Aviva on 0800 141 3430 |
| Complaints | About a claim or service: Aviva, 0800 148 8656. About how a policy was sold: Santander, 0800 171 2171. You may then be able to go to the Financial Ombudsman Service |
Is Santander life insurance good?
Santander’s policies are provided, underwritten and administered by Aviva, which reported paying 98.7% of its individual life claims in 2025. The Life Insurance Plan covers ages 18 to 77 for 1 to 50 years. It offers level, decreasing or increasing cover and includes terminal illness cover, free house purchase cover and a separation benefit for joint policies. Defaqto also rates Santander’s Over 50s Life Insurance 5 stars, and when we checked, eligible new customers could get £100 or £150 cashback.
On the downside, Defaqto gives the Life Insurance Plan and Critical Illness Plan 3 stars, and critical illness cover is a separate policy for ages 18 to 64. Santander is a bank acting as a non-advised intermediary online and by phone, and its bank-wide Trustpilot score is 3.6 out of 5. Its 2020 partnership renewal with Aviva set the life insurance agreement to run to December 2026.
The right insurer for you depends on your needs and the price you’re offered, so it’s worth comparing Santander with other insurers.
Pros
- Policies provided, underwritten and administered by Aviva
- Aviva reported paying 98.7% of life claims in 2025
- Terminal illness cover, free house purchase cover and Protection Promise cover included on the Life Insurance Plan
- Choice of level, decreasing or increasing cover, for one person or two
- Over 50s Life Insurance rated 5 stars by Defaqto, with guaranteed acceptance
- Cashback of £100, or £150 for some Santander customers
Cons
- Life Insurance Plan and Critical Illness Plan rated 3 stars by Defaqto
- Critical illness cover is a separate policy, for ages 18–64 only
- Non-advised: Santander gives information but not advice
- Trustpilot score of 3.6 / 5 for Santander as a whole
- No cash-in value on any of the policies
- The Over 50s payout is fixed and could be less than the premiums paid
Santander life insurance policy documents
Before you take out a policy, it’s worth reading the policy summary and conditions for the exact product you’re offered. These official documents are published by Aviva and Santander:
-
Life Insurance Plan policy summary (opens in a new tab)
What the Life Insurance Plan covers, who can apply, the three types of cover and the included benefits.
-
Life Insurance Plan policy conditions (opens in a new tab)
The full terms of the Life Insurance Plan, including definitions, house purchase cover and separation benefit.
-
Critical Illness Plan policy summary (opens in a new tab)
The critical illnesses covered, additional critical illness benefit and children’s benefit.
-
Critical Illness Plan policy conditions (opens in a new tab)
Full definitions of the covered critical illnesses and the policy terms.
-
Over 50s Life Insurance policy summary (opens in a new tab)
How the over 50s plan works, including premiums, the first-year rules and exclusions.
-
Over 50s Life Insurance policy conditions (opens in a new tab)
The full terms of the Over 50s policy, including definitions and when it pays out.
-
Cashback terms and conditions (opens in a new tab)
Who qualifies for the £100 or £150 cashback and when it’s paid.
-
Terms of Business – Life Protection Online (opens in a new tab)
How Santander arranges policies online, how it’s paid and how to complain.
-
Aviva guide to protection trusts (opens in a new tab)
Aviva’s guide to its protection trusts and inheritance tax.
-
Aviva Survivor Trust form (opens in a new tab)
The trust deed for Aviva joint life policies.
-
Aviva Discretionary Gift Trust form (opens in a new tab)
The trust deed for Aviva single or joint life policies.
Documents are published by Aviva and Santander and open on their websites. They may be updated — the version you receive with your policy is the one that applies.
Santander life insurance FAQs
You can apply for the Life Insurance Plan between the ages of 18 and 77, and the policy must end before the oldest person covered turns 91. The Critical Illness Plan is for ages 18 to 64 (ending before age 76), and Over 50s Life Insurance is for ages 50 to 80.
Aviva provides, underwrites and administers Santander’s Life Insurance Plan, Critical Illness Plan and Over 50s Life Insurance, and Santander can only offer life and critical illness policies from Aviva. Life policies taken out before 30 June 2011 are underwritten by Royal London.
Yes. Claims on Santander’s Aviva-underwritten policies are paid by Aviva. In 2025 Aviva reported paying 98.7% of individual life claims (over £860 million) and 90.7% of critical illness claims across all its individual protection policies, not only Santander’s.
When you apply for cover you will be asked questions about your health and lifestyle, and based on this and the amount of cover requested, the insurer will decide if a medical is required or not.
Santander says that in most cases you can get life insurance even with medical conditions. You need to tell it about them when asked, and you might need a medical exam, which it pays for. Over 50s Life Insurance has guaranteed acceptance for ages 50 to 80 and doesn’t ask about your health: you answer questions about your date of birth and whether you smoke.
Yes. Santander says you can put your life insurance policy in trust so the proceeds don’t form part of your estate for inheritance tax purposes. It links to Aviva’s trust guide, the Aviva Survivor Trust form and the Aviva Discretionary Gift Trust form, and suggests specialist legal advice if you’re unsure.
Yes. When we checked on 25 September 2026, Santander offered £150 cashback to eligible Santander mortgage, Private Banking, Select and Edge current account customers, and £100 to other customers. It applies to one new Life Insurance Plan, Critical Illness Plan or Over 50s policy with a minimum 24-month term. Santander aims to pay it 280 days after the policy starts, and can withdraw the offer at any time.
With increasing cover on the Life Insurance Plan, Aviva raises your cover each year in line with CPI (up to 10%). It does this without further health and lifestyle questions, and you can decline any increase. To increase the cover amount on a Life Insurance Plan in other cases, Aviva issues a new policy alongside your original one. It may ask further health and lifestyle questions and, depending on your answers, may not be able to make the change. Over 50s policies can’t be changed once started, but you could take out another policy, subject to availability, eligibility and the £100 monthly premium limit.
Yes. There’s a 30-day cooling-off period, and cancelling within it gives you a refund of any premiums paid. You can still cancel after 30 days, but your premiums won’t be refunded and the policies have no cash-in value.
The Life Insurance Plan doesn’t pay out if the person covered dies by suicide or intentional self-inflicted injury within 12 months of the start date. On Over 50s Life Insurance, only accidental death is covered in full in the first year, and suicide is excluded from that cover.
If you're struggling or thinking about suicide, our guide to suicide and life insurance lists where to get support straight away.
For policies taken after 30 June 2011, use Aviva’s online claims notification form or call 0800 158 3467 (Monday to Friday, 8am to 6pm). For life policies taken before 30 June 2011, call Royal London on 0345 741 3002. For the SunLife Guaranteed Over 50 Plan, call SunLife on 0800 008 6060.
Sources
The facts on this page come from these sources.
- Santander UK — Santander lights up its UK headquarters in pride as headline sponsor of Milton Keynes Pride Festival (press release, 6 September 2024) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Wikimedia Commons — Wikimedia Commons file page - Unity Place, Milton Keynes - geograph.org.uk - 7661636.jpg (photo, CC BY-SA 2.0) (opens in a new tab), commons.wikimedia.org, accessed 25 September 2026.
- Santander UK — Our history - the history of Santander in the UK (timeline 1849-2026) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Companies House — Companies House - SANTANDER UK PLC (company 02294747) overview (opens in a new tab), find-and-update.company-information.service.gov.uk, accessed 25 September 2026.
- Aviva Life & Pensions UK Limited (for Santander UK plc) — Santander Life Insurance Plan policy summary (SD06001, 08/2025) (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Aviva Life & Pensions UK Limited (for Santander UK plc) — Santander Critical Illness Plan policy summary (SD08001, 11/2024) (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Aviva Life & Pensions UK Limited (for Santander UK plc) — Santander Over 50s Life Insurance policy summary (SD11001, 09/2025) (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Santander UK — Our Terms of Business – Life Protection Online (LIFE 1046 SEP 25) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Santander UK — Life insurance (life protection overview) page (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Santander UK — Over 50s Life Insurance page (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Aviva Life & Pensions UK Limited (for Santander UK plc) — Santander Life Insurance Plan policy conditions (SD06002, 10/2023) (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Aviva Life & Pensions UK Limited (for Santander UK plc) — Santander Critical Illness Plan policy conditions (SD08002, 10/2023) (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Santander UK — Critical illness cover (Critical Illness Plan) page (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Aviva Life & Pensions UK Limited (for Santander UK plc) — Santander Over 50s Life Insurance policy conditions (SD11002, 09/2021) (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Defaqto — Defaqto Star Ratings (Life & Protection) for Santander (opens in a new tab), defaqto.com, accessed 24 September 2026.
- Trustpilot — Trustpilot - Santander (www.santander.co.uk) company reviews, all Santander UK products (not life-insurance specific) (opens in a new tab), uk.trustpilot.com, accessed 25 September 2026.
- Aviva plc — Underwriter Aviva claims statistics 2025 - Aviva paid nearly £2 billion in protection claims in 2025 (all Aviva policies, not Santander-only) (opens in a new tab), aviva.com, accessed 25 September 2026.
- Santander UK — Up to £150 cashback on Santander life protection: terms and conditions (LIFE MC0476 AUG 25) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Smart Money People — Smart Money People - Santander reviews, all Santander UK products (company-wide score) (opens in a new tab), smartmoneypeople.com, accessed 25 September 2026.
- Santander UK — About Santander UK (overview and 2025 figures) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Santander UK — Santander and Aviva announce renewal of home and life insurance partnership (press release, 5 March 2020; Wayback Machine capture 10 May 2026) (opens in a new tab), web.archive.org, accessed 25 September 2026.
- Santander UK — Santander UK completes cash acquisition of TSB Banking Group (press release, 1 May 2026) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Santander UK — Making a claim, finding your policy documents and other information about your policy (life, over 50s and trust sections) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Santander UK — Family and lifestyle insurance (Life Insurance Plan and Critical Illness Plan) page (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Santander UK — TSB has now become part of the Santander group (customer information page) (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Fairer Finance — Fairer Finance - life insurance customer experience ratings table, Autumn 2026 (Santander row: claims score, complaints, transparency, overall) (opens in a new tab), fairerfinance.com, accessed 25 September 2026.
- Smart Money People — Smart Money People - Santander: Life Insurance reviews (product score, 3 reviews) (opens in a new tab), smartmoneypeople.com, accessed 25 September 2026.
- Fairer Finance — Fairer Finance - over 50s life insurance product ratings (Santander Over 50s Life Assurance) (opens in a new tab), fairerfinance.com, accessed 25 September 2026.
- Santander UK — Mortgage life insurance page (opens in a new tab), santander.co.uk, accessed 25 September 2026.
- Aviva — Aviva’s protection trusts and inheritance tax guide (AL53005, 06/2023), linked by Santander as “Aviva Guide to Protection Trust” (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Aviva — Aviva Survivor Trust (protection) form (AL53002, 08/2026), linked by Santander (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Aviva — Aviva Discretionary Gift Trust (protection) form (AL53003, 08/2026), linked by Santander (opens in a new tab), static.aviva.io, accessed 25 September 2026.
- Aviva plc — Underwriter Aviva claims statistics 2024 - Aviva paid out £1.89bn to support protection customers in 2024 (all Aviva policies, not Santander-only) (opens in a new tab), aviva.com, accessed 25 September 2026.
- Aviva plc — Underwriter Aviva claims statistics 2023 - £1.18bn paid out on more than 50,600 Aviva individual protection claims in 2023 (all Aviva policies, not Santander-only) (opens in a new tab), aviva.com, accessed 25 September 2026.
- Aviva — Make a life insurance claim - online claim form and Aviva life claims phone numbers (underwriter Aviva's claims page; the Santander claims page links to Aviva's online claims notification form) (opens in a new tab), aviva.co.uk, accessed 25 September 2026.
- Santander UK — Bereavement - how to tell Santander about a death, bereavement team contact details and Santander Life Insurance numbers (opens in a new tab), santander.co.uk, accessed 25 September 2026.
Related pages
-
Best life insurance
What to compare when you choose a policy.
-
Term life insurance
Cover for a set number of years, with level or decreasing cover.
-
Decreasing term life insurance
The payout falls over the term, often in line with a mortgage.
-
Mortgage life insurance
Match your cover to your mortgage and protect your home.
-
Whole of life insurance
Lifelong cover and how it differs from term cover.
-
Over 50s life insurance
Guaranteed acceptance for ages 50–85, and what to check before you buy.